Credit Card Debt After Death: Who Pays and What to Do
Credit card debt is usually paid from estate property, not a relative's own money. Confirm who is legally responsible, whether the claim is valid, and the state deadline before paying or negotiating.
When someone dies, their credit card debt is usually paid from the money and property they left behind, not your own money. Before acting, confirm responsibility, the balance, and state creditor-claim rules.
Rules vary by state. This is general information, not legal advice.
Key Takeaways
- Being the executor does not make you responsible for the balance.
- Cosigners, joint holders, and some surviving spouses may have separate responsibility.
- Claim deadlines and their effects vary. Do not rely on a national range.
- Verify the balance and payment priority before paying a claim or beneficiaries.
Who Is Responsible for Credit Card Debt After Death
The Consumer Financial Protection Bureau says debts are generally paid from estate property. If the estate cannot pay and no one else shares responsibility, the balance may go unpaid.
You do not inherit a parent's card balance merely because you are their child. Separate responsibility may arise if you cosigned, held the account jointly, or fall under a state-law spouse exception. An authorized user generally does not owe the balance.
An executor can face a surcharge for mishandling estate money. That risk comes from their actions, not the role itself.
Understanding Creditor Claim Deadlines and Statute of Limitations
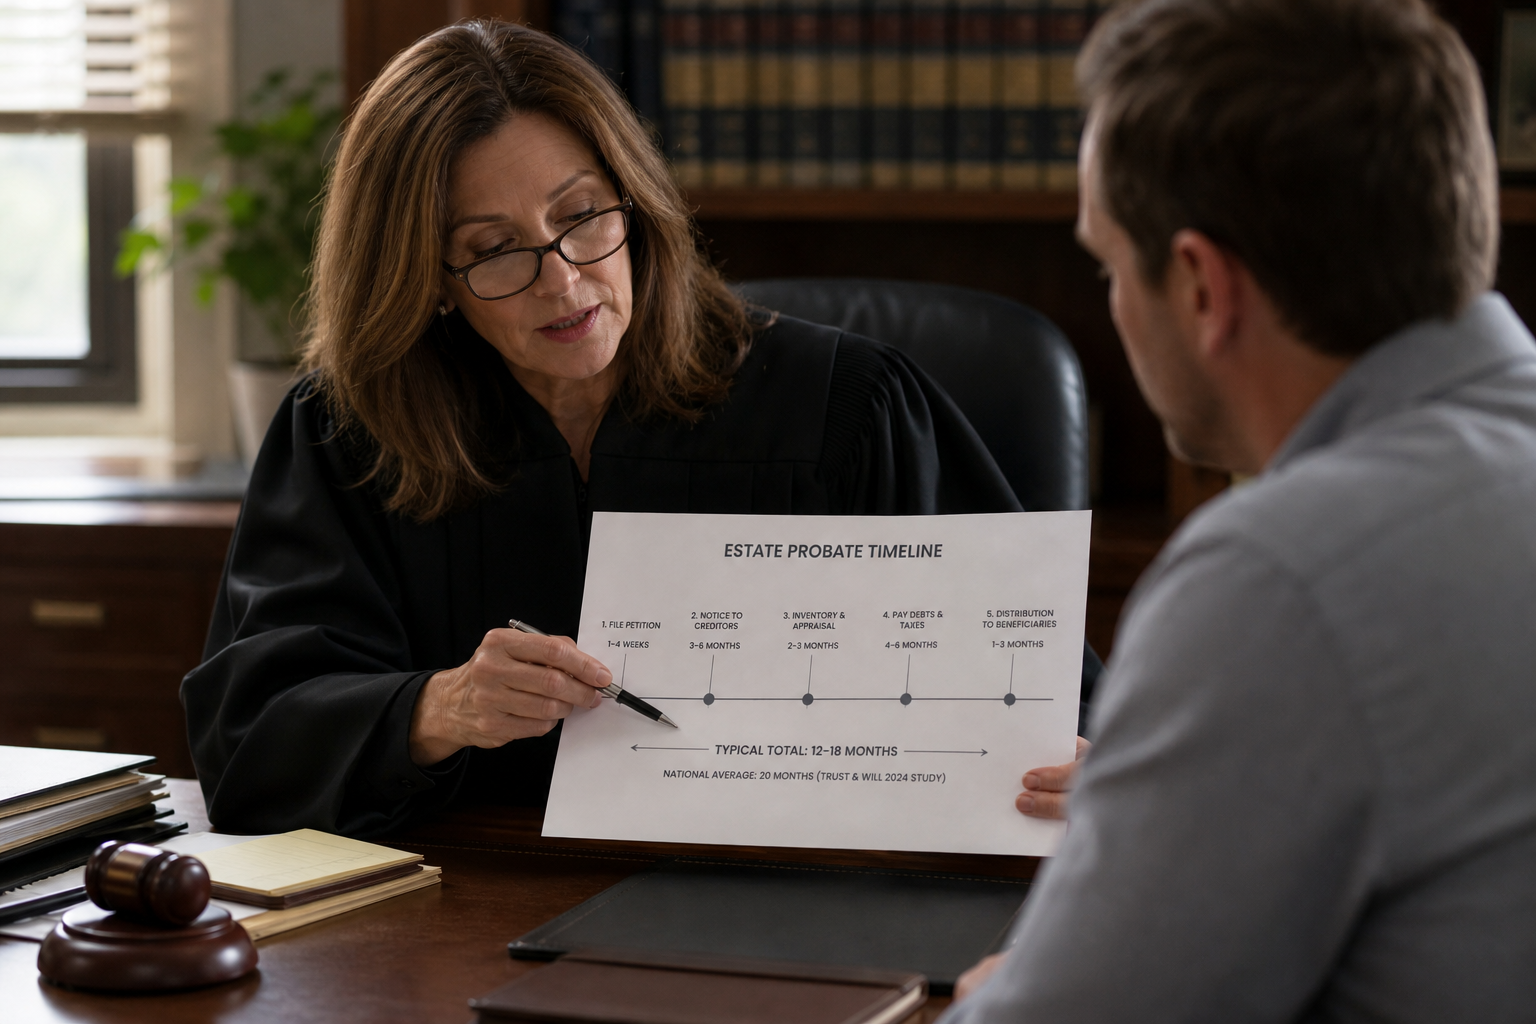
A probate claim deadline differs from the card debt's ordinary limitation period. Its clock may start when the court issues authority, notice is published, or a creditor receives direct notice. Check the governing statute before treating a claim as late.
How the Executor Must Notify and Verify Creditors
Use statements, mail, and credit reports to find creditors. Follow state rules for notice, publication, and objections.
Ask the issuer for the balance in writing. Under federal credit-card rules, it must respond to an estate administrator in a timely manner. Thirty days is a safe harbor. It generally cannot add fees or increase the annual percentage rate after the request. Joint accounts are treated differently.
If a third-party collector contacts you, request the validation information required by federal law. Use the state's probate procedure to dispute the estate claim.
When an Estate Cannot Pay All Debts: Priority Order Explained
Do not pay unsecured cards simply because they called first. State law controls which expenses and claims get paid first when the estate lacks enough money.
California and Florida, for example, place administration expenses and other protected classes ahead of general unsecured debt. Preserve cash for higher-priority items before paying a card claim.
When Credit Card Companies May Negotiate an Estate Debt
A card issuer may consider less for a disputed claim, an estate that cannot pay every claim, or prompt payment. No discount is guaranteed. Base the offer on available cash, higher-priority claims, and the amount the estate can lawfully pay. Check whether state law requires approval.
Writing a Credit Card Debt Settlement Letter After Death
Identify the estate, court case, account ending digits, and your authority to act. Send copies, not original court papers or death certificates.
Sample wording: “As executor of the Estate of [Name], I offer $[amount] to settle account ending [last four]. This offer is conditioned on your written agreement that payment will fully satisfy the account and that you will withdraw any related estate claim.”
Keep the signed acceptance, proof of payment, and written confirmation of a zero balance.
Common Mistakes That Can Make Executors Personally Liable
Reserve enough for expenses, taxes, and valid claims before distributing money. An early distribution can trigger a refund order or a surcharge against the executor.
Do not pay claims out of order. Stop using your loved one's credit or debit card because an authorized user's permission may end at death. Notify the issuer and use an estate account after you have authority.
State-Specific Considerations for Debt Negotiation
These examples show why a single nationwide deadline is unsafe:
StateRule to verifyWhy the wording mattersCaliforniaThe later of four months after letters first issue or 60 days after notice is delivered.Probate Code §9100 also preserves other limitation rules.FloridaThe later of three months after first publication or 30 days after service for a creditor entitled to notice.§733.702 is separate from Florida's two-year outer bar.New YorkSeven months after letters first issue affects an executor's protection for good-faith payments.SCPA §1802 is not an automatic deadline that erases every late claim.
Spousal liability, notice duties, claim objections, compromise approval, and payment priority also depend on state law.
Protecting Estate Assets During the Settlement Process
Notify each issuer, stop recurring charges, and request written confirmation that the account is closed or restricted.
Tell Equifax, Experian, and TransUnion about the death. TransUnion says the file cannot receive a standard security freeze, but the bureau can add a death indicator.
Secure property, redirect mail, and keep a dated log of creditor calls, claims, offers, and responses.
How Alix Simplifies Debt Negotiation for Executors
Alix provides end-to-end estate-settlement support. An Estate Settlement Specialist organizes creditor balances, records, responses, and communications.
Licensed counsel handles legal advice and required notices, filings, disputes, and approvals. You may use an attorney from Alix's network, included in one transparent fee, or your own.
See how Alix handles debt and other estate obligations within the full settlement process.
Credit-card claims are one part of the full process. Estate settlement services can help keep creditor work, estate records, taxes, property, and distributions organized as one plan.
Final Thoughts on Executor Responsibilities for Credit Card Debt
Before negotiating, verify who owes the balance, which deadline applies, and where the claim sits in the payment order.
FAQs
There is no single nationwide deadline. The period may run from the date the court issues authority, first publication, or direct notice. Check the statute and probate-court instructions for the state handling the estate before rejecting a claim as late.
Usually, you should not make final distributions until you identify valid claims and reserve enough for higher-priority expenses. State law may allow an interim distribution with safeguards. Paying too early can lead to a refund order or a surcharge against the executor.
No authoritative national percentage applies. Base an offer on the verified balance, available estate cash, higher-priority claims, and the creditor's likely recovery. Get written acceptance before paying. Confirm whether state law requires consent from beneficiaries or approval from the probate court.
Not merely because you are the executor. You may have separate responsibility if you cosigned, held the card jointly, or fall under a state-law exception. You can also face liability for mishandling estate assets. An authorized user generally does not owe the existing balance.
Stop using the card and notify the issuer. Permission for an authorized user may end when the responsible cardholder dies, so new charges may be unauthorized or become your responsibility. Once you have authority, pay approved expenses from an estate account and keep the supporting receipts.

Related resources