What to Do When a Parent Dies With a Reverse Mortgage (September 2026)
Losing a parent is hard enough. Finding out there's a reverse mortgage on the house adds a whole other layer of urgency on top of an already overwhelming situation. The loan is now due, and the servicer has sent or will soon send a notice that starts a real deadline, but knowing how the process actually works makes it a lot more manageable than it sounds.
Key Takeaways:
- The reverse mortgage loan becomes due when your parent dies; you are not personally liable, but the estate must act within the servicer's timeline.
- For HECMs, you can generally satisfy the debt by paying 95% of the appraised value even if the balance exceeds what the home is worth, in most cases.
- Heirs generally have around 30 days to declare intent after the due-and-payable notice, with extensions typically available up to around 12 months in many cases, subject to servicer approval and HUD guidelines.
- Probate averages 20 months nationally, per a Trust & Will 2024 study, while the servicer's clock typically runs on its own shorter schedule, which means you may be managing both at once.
- Alix coordinates the servicer track and the probate track as one process, handling appraisals, insurance, property coordination, and 150+ administrative tasks under one estate-funded fee.
What a Reverse Mortgage Is and Why It Changes After Your Parent Dies
A reverse mortgage lets a homeowner aged 62 or older borrow against their home's equity without making monthly payments. The balance grows over time as interest accrues, and the loan generally stays in place as long as the borrower lives there. As the CFPB explains, reverse mortgage loans typically must be repaid when the last borrower dies, usually by selling the home.
The loan did not disappear with your parent. It became due, and the estate is now responsible for resolving it.
HECMs vs. Proprietary Reverse Mortgages: Why the Type Matters
The loan documents your parent signed determine which rules govern the repayment process. Most borrowers have a Home Equity Conversion Mortgage, or HECM, which is the federally insured reverse mortgage program administered through FHA-approved lenders and backed by HUD. If your parent's loan is a HECM, specific federal protections apply: heirs can satisfy the debt by paying 95% of the home's appraised value if the balance exceeds it, and the loan is non-recourse, meaning no one is personally liable for any shortfall.
Proprietary reverse mortgages are private products with terms set by the lender, not the federal government. The 30-day response window, the 95% payoff option, and the non-recourse protections that come with HECMs may not carry over. Before assuming any specific rule applies, pull the promissory note and loan agreement from your parent's files. The servicer's due-and-payable notice should also identify the loan type. If you are uncertain, call the servicer directly and ask.
Who Is Responsible for the Loan After Your Parent Dies
You are not personally on the hook for the loan balance. For a HECM, the debt is tied to the home, not to you. If the loan balance exceeds what the home is worth, the CFPB confirms that heirs can satisfy the debt by paying 95% of the appraised value. You walk away without owing the difference out of pocket.
What you are responsible for is deciding what happens to the property. The estate holds the home, and someone, usually the executor, has to make a decision within the servicer's timeline. That is a fiduciary obligation, not a personal financial liability.
Two situations work differently:
- If your parent had a co-borrower on the loan, that person can remain in the home and the loan does not come due yet.
- Eligible non-borrowing spouses may also qualify to stay, depending on when the loan was originated and whether they meet HUD's criteria.
- Adult children inheriting the property have no such deferral option. The loan is due, and the clock is running.
The Timeline You Are Working With
The clock starts when the servicer sends the due-and-payable notice. That notice is not a foreclosure filing. It is a formal signal that the loan has matured and the estate needs to respond.
According to the CFPB, heirs generally have around 30 days from that notice to indicate their intent, whether that is selling, paying off the loan, or turning the property over. After that, the timeline can typically be extended up to six months to sell the home or secure financing, with HUD-approved extensions of roughly 90 days each bringing the total to around 12 months in many cases.
A few things worth knowing:
- Extensions are not automatic; the estate generally needs to communicate with the servicer and show active progress toward resolution.
- Exact deadlines vary by servicer and circumstance, so treat every figure here as a general framework, not a fixed guarantee.
- Ignoring the notice is the one move that collapses your options fastest.
The window is real, but workable if you act early.
The First Steps to Take Right Now
Every step below buys you time or information, and together they keep the estate in control of the outcome.
- Locate the loan documents. Find the promissory note, deed of trust, and any correspondence from the servicer. These tell you the loan type, the servicer's contact information, and the original terms.
- Get certified copies of the death certificate. You will need multiple copies, typically at least five, for the servicer, probate court, financial institutions, and any title work that follows.
- Notify the servicer promptly. Contact them as soon as you are able, inform them the borrower has passed, and ask what documentation they require. Request the payoff statement and a current account statement in writing.
- Request a formal payoff figure. Compare it against a rough sense of the home's current value before making any decisions about selling or refinancing.
- Consult a HUD-approved housing counselor or attorney. HUD offers free or low-cost HECM counseling, and an early session can clarify which options are actually on the table for your specific loan.
None of these steps commits the estate to a particular outcome. They simply keep your options open while the timeline is still on your side.
Your Four Options for Resolving the Reverse Mortgage
Four paths exist, and which one fits depends on the equity position and what you want to do with the home.
| Option | How it works | Best fit | Personal liability |
|---|---|---|---|
| Sell the home | Estate lists and sells the property; loan is paid from proceeds. If balance exceeds value, paying 95% of appraised value satisfies the debt. | Most situations, especially where equity remains or a clean resolution is the priority | None (HECM non-recourse) |
| Pay off the loan and keep the home | Refinance into a conventional mortgage or pay the balance in cash. Amount due is the lesser of the loan balance or 95% of appraised value. | Heirs want to retain the property | None beyond the payoff amount |
| Deed-in-lieu of foreclosure | Estate voluntarily signs the property over to the lender, with no sale process and no extended timeline. | Minimal equity and no interest in selling independently | None |
| Allow foreclosure | Servicer initiates foreclosure if the estate takes no action. Least controlled outcome and typically the slowest. | Last resort when coordinating a response proves impossible | None (HECM non-recourse), but equity is lost |
Sell the home
The most common path. The estate lists and sells the property, the loan is paid from proceeds, and any remaining equity goes to the estate. If the balance exceeds the home's value, you can satisfy the debt by paying 95% of the appraised value instead of the full balance, and the lender absorbs the difference.
Pay off the loan and keep the home
If you want to hold the property, you can refinance into a conventional mortgage or pay the balance in cash. The amount due is the lesser of the loan balance or 95% of appraised value.
Deed-in-lieu of foreclosure
The estate signs the property over to the lender voluntarily, with no sale process and no extended timeline. This makes sense when equity is minimal and the estate has no interest in selling independently.
Allow foreclosure
If the estate takes no action, the servicer can eventually initiate reverse mortgage foreclosure. This is the least controlled outcome and typically the slowest, and it rarely benefits the estate, but it is an available path when coordinating a response proves impossible.
What Happens When the Loan Balance Exceeds the Home's Value
For HECMs, FHA insurance absorbs any shortfall between the loan balance and what the home is worth. You pay the lesser of 95% of the appraised value or the loan balance, and the lender takes the loss. Turning the property over entirely is also an option, with the same result: no personal liability follows.
That protection is specific to HECMs. Proprietary reverse mortgages are governed by the loan documents your parent signed, and non-recourse terms, if they exist at all, depend entirely on that contract. Read it before assuming the same rules apply.
Worth noting: genuinely upside-down estates are the minority. Among reverse mortgage estates in Alix's own CRM data, per Alix's analysis of client cases, the median home value sits well above the median loan balance, with meaningful equity remaining in most cases.
How Probate Intersects With the Reverse Mortgage Process
The reverse mortgage servicer and the probate court operate on completely different clocks, and those two timelines do not naturally sync.
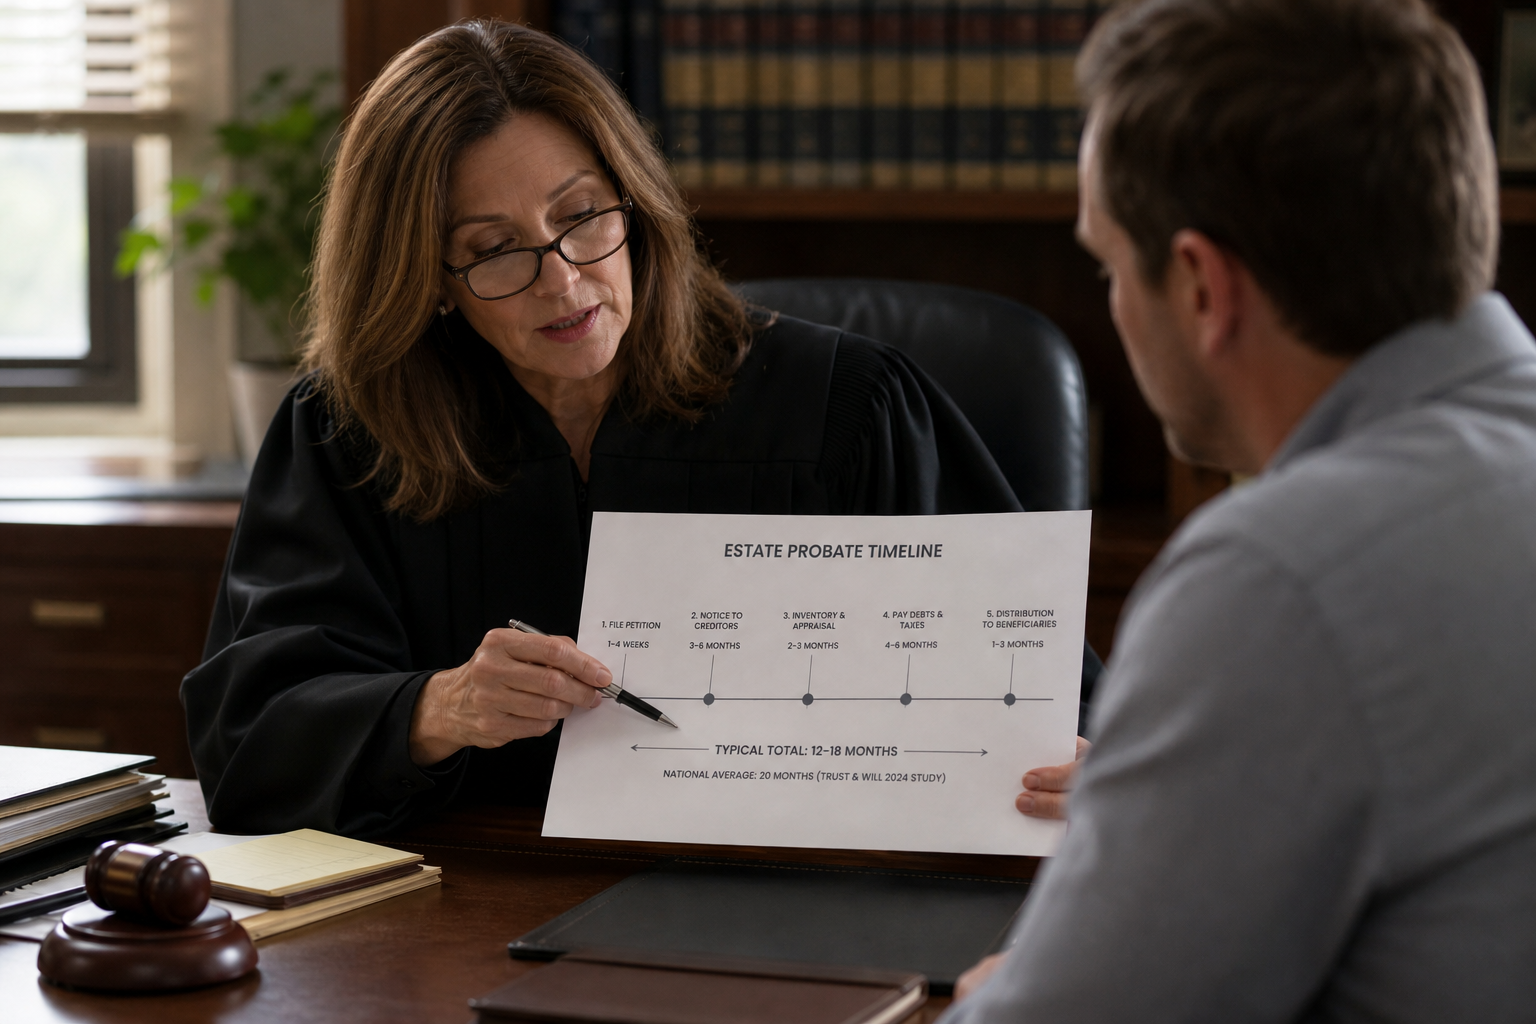
To sign a deed, execute a sale, or formally transfer the property, you generally need to be appointed executor by the probate court first. Letters testamentary, the court-issued document that gives you legal authority to act, take time to obtain. Per a Trust & Will 2024 study, the national average probate timeline is 20 months. The reverse mortgage servicer is not waiting 20 months, which means you are running two tracks at once, and the servicer's track has real deadlines attached.
Filing promptly, communicating actively with the servicer while probate is pending, and requesting extensions before they expire keeps the estate in a controlled position. Servicers generally want resolution, not foreclosure, and will work with an estate that is visibly making progress. The friction comes when probate stalls and no one has communicated with the servicer in months.
Taxes, Insurance, and Upkeep While the Estate Settles
Property taxes, homeowner's insurance, and basic maintenance remain active obligations of the estate from the day your parent died until the home is sold or transferred. The servicer monitors compliance on all three. If taxes go unpaid or the insurance lapses, the loan can be called due immediately, which compresses your timeline and removes flexibility you would otherwise have.
Vacancy creates its own complications. Standard homeowner's insurance policies often exclude or limit coverage for homes left unoccupied beyond 30 to 60 days. If the property sits empty, you may need to convert to a vacant home policy or add an endorsement before a gap opens, not after a claim.
A Few Things Worth Planning Ahead
- Utilities typically need to stay on for inspections and to prevent weather or moisture damage, even if no one is living there.
- Routine upkeep like lawn care, gutter clearing, and seasonal maintenance keeps the property insurable and preserves its value ahead of selling the inherited house.
- If you live out of state, a property manager or a trusted neighbor with written authorization from the estate is a workable arrangement.
The servicer's loan agreement gives them the right to inspect the property. A neglected or uninsured home puts the estate's equity at risk at exactly the moment you need it most.
How Alix Helps Executors Manage a Reverse Mortgage Estate
Running two tracks at once, the servicer's and the probate court's, is genuinely hard to do alone. The reverse mortgage timeline does not pause while you file for letters testamentary, wait on court dates, track down your parent's accounts, or figure out what happens to the car.
Alix is a human-led estate settlement service built for exactly this kind of compounded complexity. Based on Alix's analysis of client cases, settling an estate typically involves 600+ hours of work over 18 months. When a reverse mortgage is in the picture, that workload grows, because the home decision sits on a compressed servicer timeline while everything else runs in parallel.
Alix's estate settlement specialists handle the day-to-day work: real estate access and coordination, locksmith access, routine maintenance, appraisals, insurance continuation, utility transfers, asset discovery, creditor management, beneficiary communication, and more than 150 administrative tasks that do not require a law license, all part of a detailed executor checklist. An attorney from Alix's network is included in the one transparent estate-funded fee, covering licensed legal work like court filings, formal creditor notices, and probate hearings. You do not have to source your own attorney for standard probate work.
The result is one coordinated estate settlement process across both tracks, whether the estate goes through probate or is administered through a trust, instead of you managing the servicer on one side and the court or trustee obligations on the other while also fielding calls from beneficiaries and figuring out the water bill.
Final Thoughts on Managing a Reverse Mortgage After Losing a Parent
You are not personally liable for the balance, and you have real options: selling, refinancing, or turning the property over entirely. The key is staying active with the servicer and keeping probate moving so the two timelines don't collide. Start your Alix onboarding if you want one coordinated process handling both tracks from here.
FAQ
What happens to a reverse mortgage when your parent dies?
The loan becomes due immediately upon your parent's death. For a HECM, the servicer issues a due-and-payable notice, and the estate generally has 30 days to indicate its intent, with extensions typically available up to around 12 months in many cases, subject to servicer approval and HUD guidelines. Your parent's home must be sold, refinanced, or transferred to the lender to satisfy the debt.
HECM vs. proprietary reverse mortgage after a parent dies: what's the difference for heirs?
A HECM comes with federal protections: you can satisfy the debt by paying 95% of the appraised value even if the loan balance exceeds it, and no personal liability follows for any shortfall. Proprietary reverse mortgages are governed by the private loan documents your parent signed, and those protections may not exist, so read the promissory note before assuming any specific rule applies.
Can a reverse mortgage loan balance exceed what the home is worth, and do heirs owe the difference?
For HECMs, no. The loan is non-recourse, and FHA insurance absorbs any shortfall. You pay the lesser of 95% of the appraised value or the loan balance, and that is the end of your exposure. Proprietary loans depend entirely on the contract terms, so check the loan documents to confirm whether non-recourse protection applies.
How do I manage a reverse mortgage servicer's deadline while probate is still pending?
File for letters testamentary as quickly as possible, then contact the servicer right away and communicate actively while probate is pending. Servicers generally will work with an estate that shows visible progress toward resolution. Request extensions before they expire, not after, and document every interaction in writing to protect the estate's position.
What service handles both the probate process and the reverse mortgage property obligations for an executor?
Alix is a human-led estate settlement service built for exactly this kind of compounded situation. Alix's estate settlement specialists coordinate real estate access, appraisals, insurance continuation, utility transfers, and creditor management alongside more than 150 administrative tasks, while a probate attorney from Alix's network handles court filings and licensed legal work, all under one transparent estate-funded fee.

Related resources