Here is what happens to a loved one's bank account when they pass without a beneficiary: the money doesn't transfer on its own. It gets frozen, absorbed into the estate, and sits there until the probate court authorizes what happens next. Who gets the money, and how long it takes, comes down to whether a will exists, what state you're in, and what type of account it actually is.
Key Takeaways:
- A sole-owned account with no beneficiary freezes at death and typically needs probate first, unless a small estate threshold applies.
- A will does not unlock the account; you need letters testamentary from probate court.
- Creditors are paid before heirs; early distributions can make you personally liable for any shortfall.
- A POD/TOD designation, joint ownership with survivorship, or a revocable living trust keeps an account out of probate.
- Alix is a human-led estate settlement service that folds bank account closure into one coordinated process with 150+ other administrative tasks.
What Happens to a Bank Account When a Loved One Passes Without a Beneficiary
When a sole account holder dies without a named beneficiary, the account becomes part of the estate and stays frozen until the legal process catches up.
That process is probate. A bank account solely in your loved one's name becomes estate property, and a court action must be filed to access and distribute it. Who receives the money depends on whether a valid will exists: with one, the account goes to whoever is named; without one, intestate succession laws decide.
How Banks Find Out About a Death
Banks don't monitor death records in real time, so notification almost always has to come from someone who knows.
The most direct path is you, the executor or next of kin, contacting the bank. According to Mount Sinai Memorial Parks, you'll typically need a certified death certificate, your loved one's full legal name, Social Security number, and account numbers. Banks can also learn indirectly through the Social Security Administration, unclaimed property databases, or obituary listings, then place a hold on the account to prevent unauthorized withdrawals while the legal process plays out.
Why Account Type Determines Everything
Three account setups lead to different outcomes:
- Sole-owned, no beneficiary: funds freeze and must pass through probate first.
- Joint account with survivorship rights: as the Consumer Financial Protection Bureau explains, the money passes to the surviving owner, skipping probate.
- POD or TOD account: the named person collects funds with a death certificate and ID, bypassing probate.
Confirm which category applies first; it tells you whether to expect a quick transfer or a long court process.
| Account Type | Goes Through Probate? | Who Receives the Funds | What's Required to Collect |
|---|---|---|---|
| Sole-owned, no beneficiary | Typically yes (unless a small estate affidavit applies) | Heir named in will, or intestate heir if no will | Letters testamentary from probate court |
| Joint account with survivorship rights | No | Surviving joint owner | Death certificate and valid ID |
| Payable-on-death (POD) or transfer-on-death (TOD) | No | Named beneficiary | Death certificate and valid ID |
Data cited November 2026. Information subject to change.
When There Is No Will: How Intestate Succession Applies to Bank Accounts
When no will exists, state intestacy laws decide who gets the money, not the account owner.
Every state sets a default inheritance order:
- Spouses first.
- Children next, or sharing with a surviving spouse.
- Parents and siblings next, in an order that varies by state, then more distant relatives.
- If no relatives are found, funds pass to the state through escheatment.
Community property states like California, Texas, and Arizona calculate a surviving spouse's share differently than common law states.
A close friend, an unmarried partner, or a specific child the owner meant to favor generally has no claim without a will or beneficiary designation, though some states treat registered domestic partners like spouses.
When There Is a Will: The Role of Probate in Distributing Bank Funds
A will clarifies who should receive the money. It does not unlock the account.
If your loved one named you in their will but never added a beneficiary designation, the funds still enter probate. The will and the account are separate legal instruments; the bank answers to the probate court, not the document in a filing cabinet.
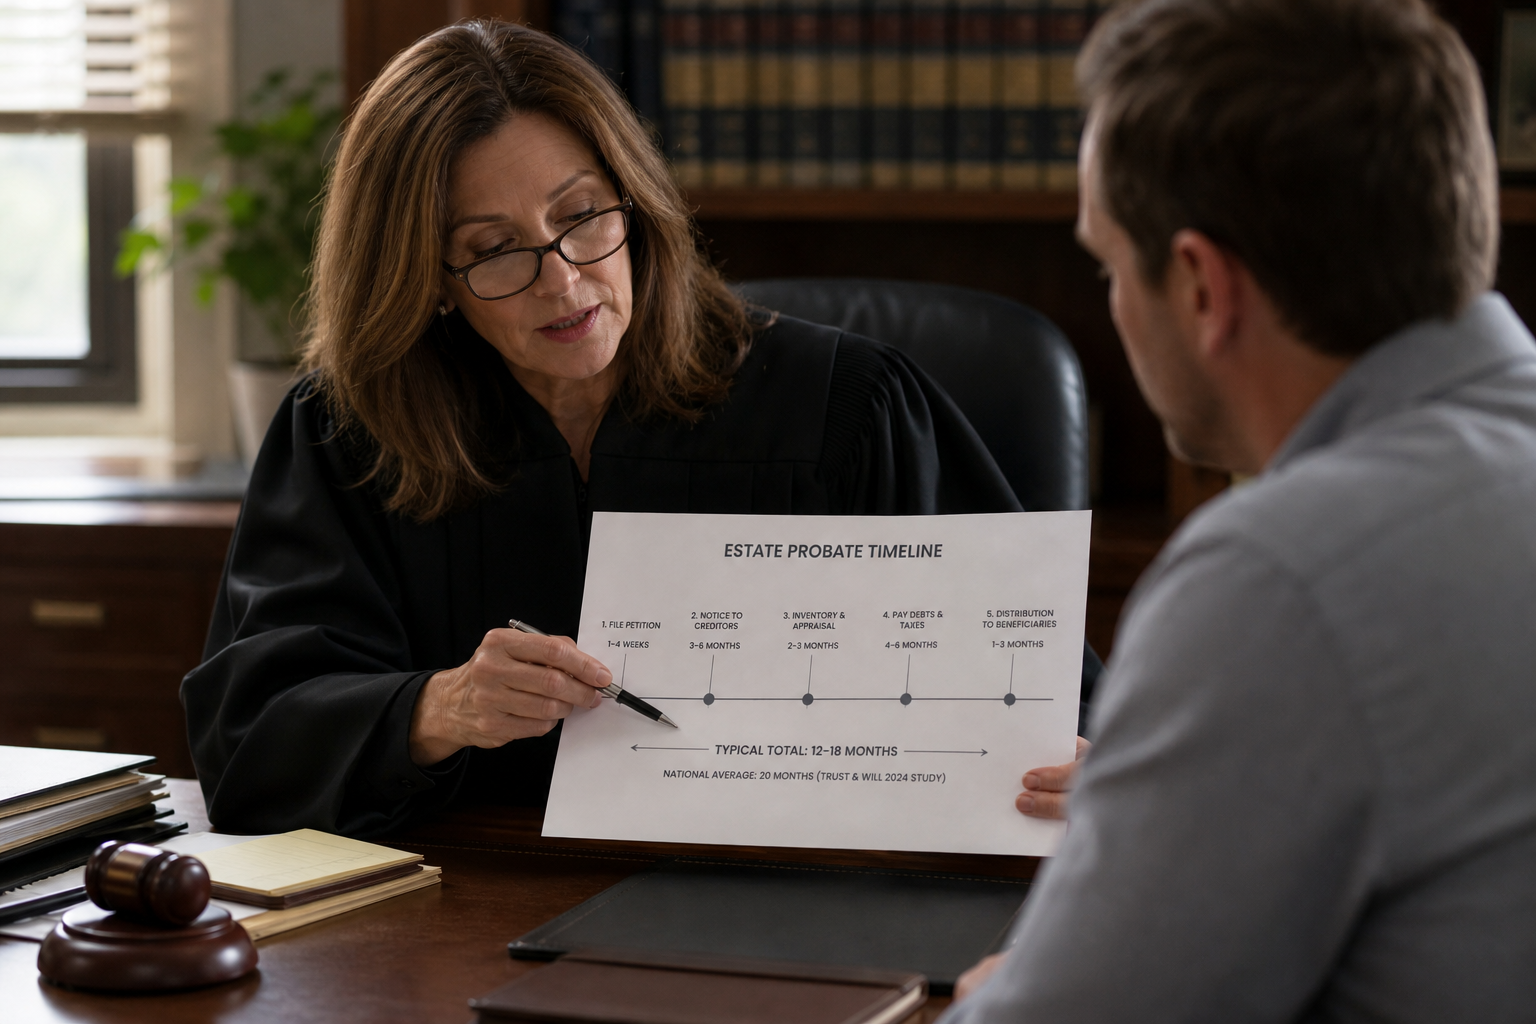
The probate court must formally appoint you as executor before you gain access. That appointment, documented through letters testamentary, lets you contact the bank and begin accessing or closing the account. Probate typically takes 12 to 18 months, and per a Trust & Will 2024 study, the national average probate timeline is 20 months, so funds in an estate account without a beneficiary can sit inaccessible a long time.
Data cited November 2026. Information subject to change.
How to Access a Loved One's Bank Account as Executor
Getting into a sole-owned account without a named beneficiary requires court authorization first. The bank won't let you in until the probate court appoints you.

Once appointed, gather these before contacting the bank:
- Certified death certificate
- Letters testamentary (or letters of administration if no will) from the probate court
- Government-issued photo ID
- Account numbers
From there, notify the bank of the death and present your documentation. Most banks will ask you to open a separate estate checking account, where funds are held until creditor claims are resolved and the court authorizes distribution. You can only apply for the estate's EIN after the court appoints you, and banks typically ask for it to open the account.
Small Estate Affidavits: When You Can Skip Probate
Many states offer a shortcut: below a set dollar threshold, an heir can present a small estate affidavit directly to the bank and collect the funds without probate.
Thresholds vary widely by state. According to the California Judicial Council form DE-300, California's limit is $208,850 for deaths on or after April 1, 2025. Check your state's figure first.
Even then, multiple accounts across banks, outstanding creditor claims, or several heirs splitting funds can turn a filing into a coordination problem, and some banks still want extra documentation before releasing anything.
Data cited November 2026. Information subject to change.
Debts, Creditors, and the Order of Payment
Creditors come before heirs. State law sets the order of payment for estate debts, and it varies by state, but a typical sequence runs as follows:
- Admin and funeral costs come first.
- Federal and state taxes follow.
- Secured debts like mortgages tie to their collateral, so the lender can generally claim that asset regardless of order.
- Unsecured debts, including medical bills, credit card debt after death, and personal loans, are paid last.
Personal Liability Is the Real Risk Here
Creditor claim deadlines vary by state, usually running a few months after notice. Distribute before that window closes, and a later valid claim can leave you personally liable.
What Happens to the Account If No Heir Claims It
If no heir steps forward before a state-set dormancy period passes, the bank hands the funds to the state's unclaimed property program, a process called escheatment.
Heirs can later file a claim with that office to recover escheated funds, but acting before the dormancy clock runs out avoids the extra paperwork.
Automatic Payments, Direct Deposits, and the Frozen Account Problem
When the account freezes, subscription services, utility autopays, insurance premiums, and mortgage drafts still try to pull funds on schedule. Most fail, triggering missed-payment notices and late fees against the estate.
Direct deposits run the opposite problem: as USAGov explains, Social Security benefits for the month of death and any later month must be returned to the government. Spending them creates a separate legal problem.
The fix is opening a dedicated estate checking account as soon as the probate court appoints you executor, so funds and obligations route there while the original account is closed or transferred.
How to Avoid This Situation: Beneficiary Designations and Account Structures
Three tools keep a bank account out of probate.
Payable-on-Death (POD) or Transfer-on-Death (TOD) Designation
Adding a named beneficiary directly to a payable-on-death bank account is the simplest fix: the named person presents a death certificate and collects the funds with no court involved. One caveat: if that beneficiary predeceases the account owner and no contingent beneficiary was named, the account reverts to the estate and probate applies again.
Joint Ownership With Rights of Survivorship
As the Consumer Financial Protection Bureau notes, most joint accounts carry rights of survivorship, so the surviving owner becomes sole owner automatically. If titled as tenants in common instead, the share belonging to the owner who passed passes to heirs through the estate. Fast and probate-free, though a joint owner has full access while both parties are alive, which may not suit every situation.
Revocable Living Trust
Placing an account in a revocable living trust removes it from the probate estate. A successor trustee steps in at death without court oversight, and the trust document controls distribution. More setup upfront, but more flexible than a simple beneficiary designation.
How Alix Coordinates the Bank Account and Estate Administration Process

A bank account with no beneficiary rarely stands alone. It tends to surface alongside asset discovery, creditor claims, probate filings, and beneficiary coordination.
When you're appointed executor, Alix's estate settlement specialists fold the bank account work into one process alongside 150+ other administrative tasks: safe deposit boxes, brokerage accounts at smaller institutions, uncashed checks, digital assets, statement requests, an estate tax ID number, freeze and closure forms, and transfer follow-up. An attorney from Alix's network handles standard probate work, and Alix's one transparent fee covers this work for the most part. Attorney work outside normal probate, such as contested matters, and back taxes are the usual exceptions.
Based on Alix's data across client cases, settling an estate involves 600+ hours of work over roughly 18 months. Specialists handle the bank, creditor, and filing steps, and an attorney from Alix's network handles the court filings, so you don't carry each one yourself.
Alix charges one transparent fee, paid from the estate's assets once they're secured, not from your pocket. Court filing fees, legal notice publication costs, and vendor costs like appraisals, real estate services, and tax prep are typically paid by the estate separately. Alix fits estates with real complexity, such as multiple accounts, creditor claims, or several beneficiaries, including estates that qualify for a small estate affidavit. If the estate is very small and simple, Alix is still an option if you're comfortable paying the standard fee for that work. Family disagreement on its own doesn't rule an estate out, but if anyone has filed with the court or hired an attorney over the dispute, or said they plan to sue, contest the will, or challenge who should be in charge, that must be fully resolved before Alix can begin.
FAQs
What happens to a bank account with no beneficiary when a loved one passes: does it go through probate automatically?
Typically, yes. When a sole-owned account has no named beneficiary, it becomes part of the estate and typically must pass through probate, unless your state's small estate affidavit threshold applies, before anyone can access or distribute the funds. The account is frozen until the probate court formally appoints an executor and issues letters testamentary, regardless of what a will says or your relationship to the person who passed.
How do you find out if a loved one's bank account had a named beneficiary?
Contact the bank directly with a certified copy of the death certificate and your loved one's account information. The bank can typically confirm whether a payable-on-death (POD) or transfer-on-death (TOD) designation exists, though it may ask for letters testamentary before sharing account details. That single fact determines whether you are looking at a direct transfer or a months-long court process.
Probate vs. beneficiary designation vs. living trust for a bank account: what's the actual difference?
A POD or TOD designation lets the named person collect funds with a death certificate. A joint account with survivorship rights passes to the surviving owner automatically. A revocable living trust takes the account out of the probate estate and puts a successor trustee in control. All three avoid the frozen-account problem.
Final Thoughts on Handling a Bank Account After Death With No Named Beneficiary
That is what happens to a loved one's bank account when they pass without a beneficiary: a court gets involved before anyone else does. Once you're appointed executor, the estate account, creditor claims, and a distribution timeline that waits for the creditor window to close all follow. Start your Alix onboarding and a specialist takes on the bank account work, with an attorney from Alix's network handling the court filings.

Related resources