Accepting an executor appointment means more than managing logistics. It means you're legally bound to act in the best interests of the estate and its beneficiaries, and to treat creditors fairly, ahead of your own. If that sounds like a high bar, it is. Here's what executor fiduciary duties actually require in practice.
Key Takeaways:
- As executor, you owe duties to beneficiaries and creditors, and you answer to the probate court, from day one.
- Pay creditors before distributing to beneficiaries; reversing that order exposes you to personal liability.
- Self-dealing, commingling funds, and missed inventory deadlines can each count as a breach, even without bad intent.
- Your documentation is your defense; courts review your records, not your intentions.
- Alix is a human-led estate settlement service that coordinates finding assets, creditor management, tax filing coordination, and beneficiary communication, with most of that work covered by one estate-funded fee (vendor costs like appraisals and tax prep are typically paid by the estate).
What It Means to Be a Fiduciary as an Executor
Being named an executor means more than organizing paperwork and making phone calls, and understanding what an executor does helps set expectations. "Fiduciary" means you're legally bound to act in the best interests of the estate and its beneficiaries, ahead of your own, from the moment you accept the appointment until the estate closes. Courts don't require proof of bad intent: if you benefit yourself, skip required steps, or mismanage assets, you can be held personally liable for the losses.
Who You Owe Fiduciary Duties To
Your duties run to a broader group than most executors expect. Beneficiaries named in the will have a direct legal interest in how you manage and distribute the estate, and can challenge your decisions in court. Creditors have standing too: you owe them fair consideration of valid claims before assets move to beneficiaries, and skipping that step exposes you to personal liability for the shortfall. The probate court oversees inventory filings, accountings, and distribution schedules, so following an executor checklist in order matters. In some states, heirs at law (relatives who would inherit under intestacy rules even if not named in the will) may also have standing, particularly if the will is contested.
The Duty of Loyalty
Every decision you make as executor has to serve the estate and its beneficiaries, not you personally. Self-dealing is the risk to watch for before you even finish how to become an estate executor. Buying estate assets below market, hiring your own company for estate services, or steering estate funds into investments you benefit from can all violate this duty, even if the deal seems fair, unless the will allows it or the court approves it. Some states require court approval before any purchase of an estate asset by an executor, regardless of price.
The Duty of Impartiality
Favoritism doesn't have to be intentional to create a problem; decisions that consistently benefit one beneficiary over others can trigger a claim. This duty means balancing beneficiaries entitled to income against those waiting on principal. A beneficiary receiving income from a rental property may prefer you hold it, while a residuary beneficiary waiting on cash may want it sold, so document why a decision serves the estate as a whole. Releasing funds to one beneficiary before others can also look like favoritism, so coordinate distributions together or document why a staggered approach was warranted.
The Duty to Preserve and Protect Estate Assets
From the moment you accept the appointment, estate assets are your responsibility. If something gets damaged, stolen, or lost before distribution, you may owe the beneficiaries out of your own pocket.

Act fast, typically within about 30 to 60 days of appointment: change locks on real property, confirm insurance coverage continues under estate ownership, and freeze financial accounts where appropriate to prevent unauthorized withdrawals. Personal property carries the same obligation. Vehicles, jewelry, artwork, and collectibles must be secured, a step covered in most step-by-step guides to settling an estate, since missing items while the estate is open can also become your responsibility.
The Duty to Inventory and Value the Estate
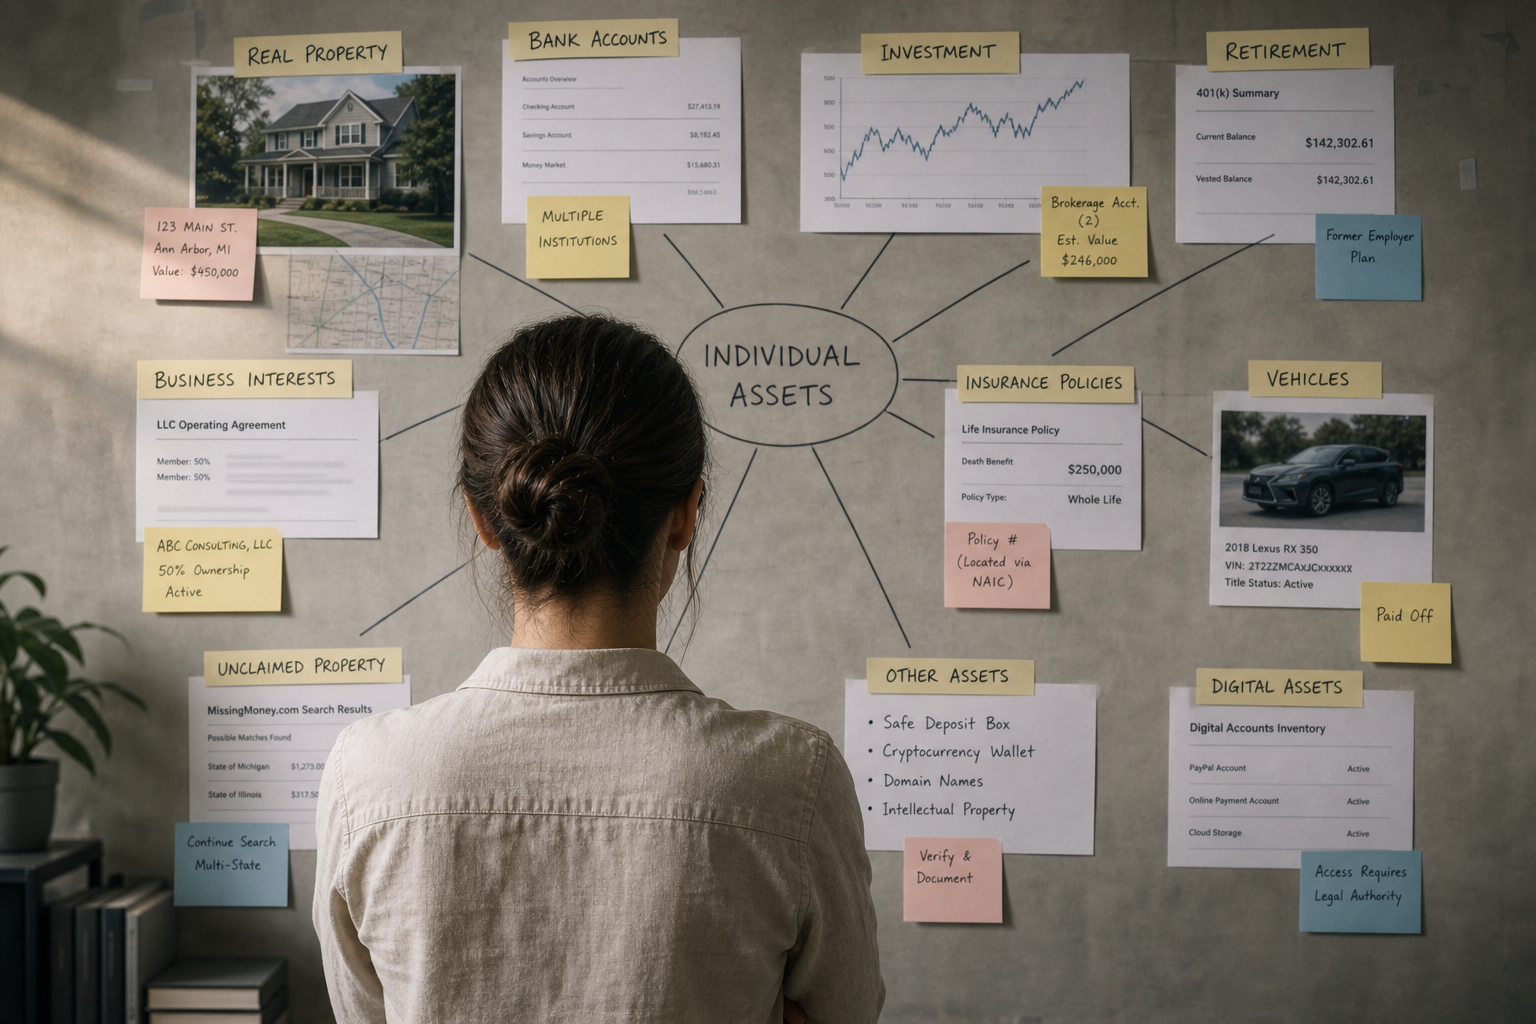
You must identify every asset the estate holds, document a value for each using credentialed appraisals where needed, and file a formal inventory with the probate court. That filing deadline often runs 60 to 90 days from your appointment, though it varies by jurisdiction, and missing it can expose you to court sanctions or removal. If an asset is missed or undervalued without a defensible basis, beneficiaries or creditors can hold you personally liable, and courts rarely accept "I didn't know it existed" as a defense when the duty to search is built into the role.
Credentialed appraisals are typically needed for assets without an obvious market price. Real property, business interests, jewelry, artwork, vehicles, and closely held stock all count among probate assets that need documented valuations from qualified appraisers; informal estimates can expose you to a breach claim.
The Duty to Notify Creditors and Pay Valid Debts
Creditors come before beneficiaries. That order is fixed by law, and reversing it exposes you to personal liability for any valid debts left unsatisfied.
Most states require a published creditor notice plus direct written notice to any creditor you know about or could reasonably locate. The claim window varies by state but commonly runs about three to seven months; Justia's creditor claims guide notes the limit is usually a few months after notice. During that window, review each claim, accept or reject it, and negotiate estate debts and creditor claims before paying valid debts and distributing what remains. The "reasonably discoverable" standard carries real weight: if a creditor had an obvious claim and you skipped notifying them, a court may hold you personally liable even after the claim window closes. Going out of order, even with good intentions, is a breach of your fiduciary duty.
Data cited November 2026. Information subject to change.
The Duty to File Tax Returns and Account for Estate Income
Tax obligations don't pause because your loved one has passed. You must file your loved one's final income tax return covering January 1 through the date of death, plus a separate estate income tax return using IRS Form 1041 if the estate generates income during administration (rent, dividends, interest). You obtain the estate's EIN only after the probate court appoints you, since that EIN is needed for the Form 1041 filing.
For larger estates, the federal estate tax return (Form 706) is due nine months after the date of death, and missing that deadline without an extension brings penalties against the estate. You're also responsible for identifying deductible administration expenses, including executor fees, attorney fees, and appraisal costs, which can reduce taxable value when documented.
The Duty to Communicate with Beneficiaries
Beneficiaries have a legal right to stay informed for the entire administration period. "Reasonable" communication varies by state, but it generally means updates at key milestones: when probate opens, when the inventory is filed, when creditor claims are resolved, and when distributions are scheduled. Silence tends to create problems: a beneficiary who hears nothing for months may assume something is wrong, and in many states, any beneficiary can petition the court to compel an accounting. Beneficiaries are generally entitled to a formal accounting of estate assets, debts paid, and expenses incurred before final distribution, so thin records or inconsistent updates leave you exposed.
What Counts as a Breach of Fiduciary Duty
Negligence crosses the line just as intentional wrongdoing does during estate administration. Courts don't require proof of intent to harm, only that you fell below a reasonably prudent standard of care.
The table below summarizes the most common breaches.
| Breach | Why It's a Problem | Potential Consequence |
|---|---|---|
| Commingling estate funds with personal accounts | Blurs the boundary between your money and the estate's money | Personal liability; supports a breach claim even if temporary |
| Distributing assets before the creditor claim window closes | Creditors come before beneficiaries by law | Personal liability for any valid claim that surfaces afterward |
| Self-dealing (buying estate property or hiring your own business) | Direct conflict of interest; your judgment is compromised by your position | Breach finding; may require court approval or unwinding the transaction |
| Failing to file a timely inventory or accounting | Core fiduciary obligation with a court-imposed deadline | Court sanctions or removal as executor |
| Allowing estate assets to deteriorate through inaction | Assets are your responsibility from the moment you accept the appointment | Personal liability for lost value; constitutes a breach on its own |
Consequences of Breaching Your Fiduciary Duty
A breach finding carries consequences beyond a court lecture. If a court determines your actions caused losses to the estate, you pay the difference out of pocket, whether that means restoring estate funds or reimbursing beneficiaries for a shortfall.
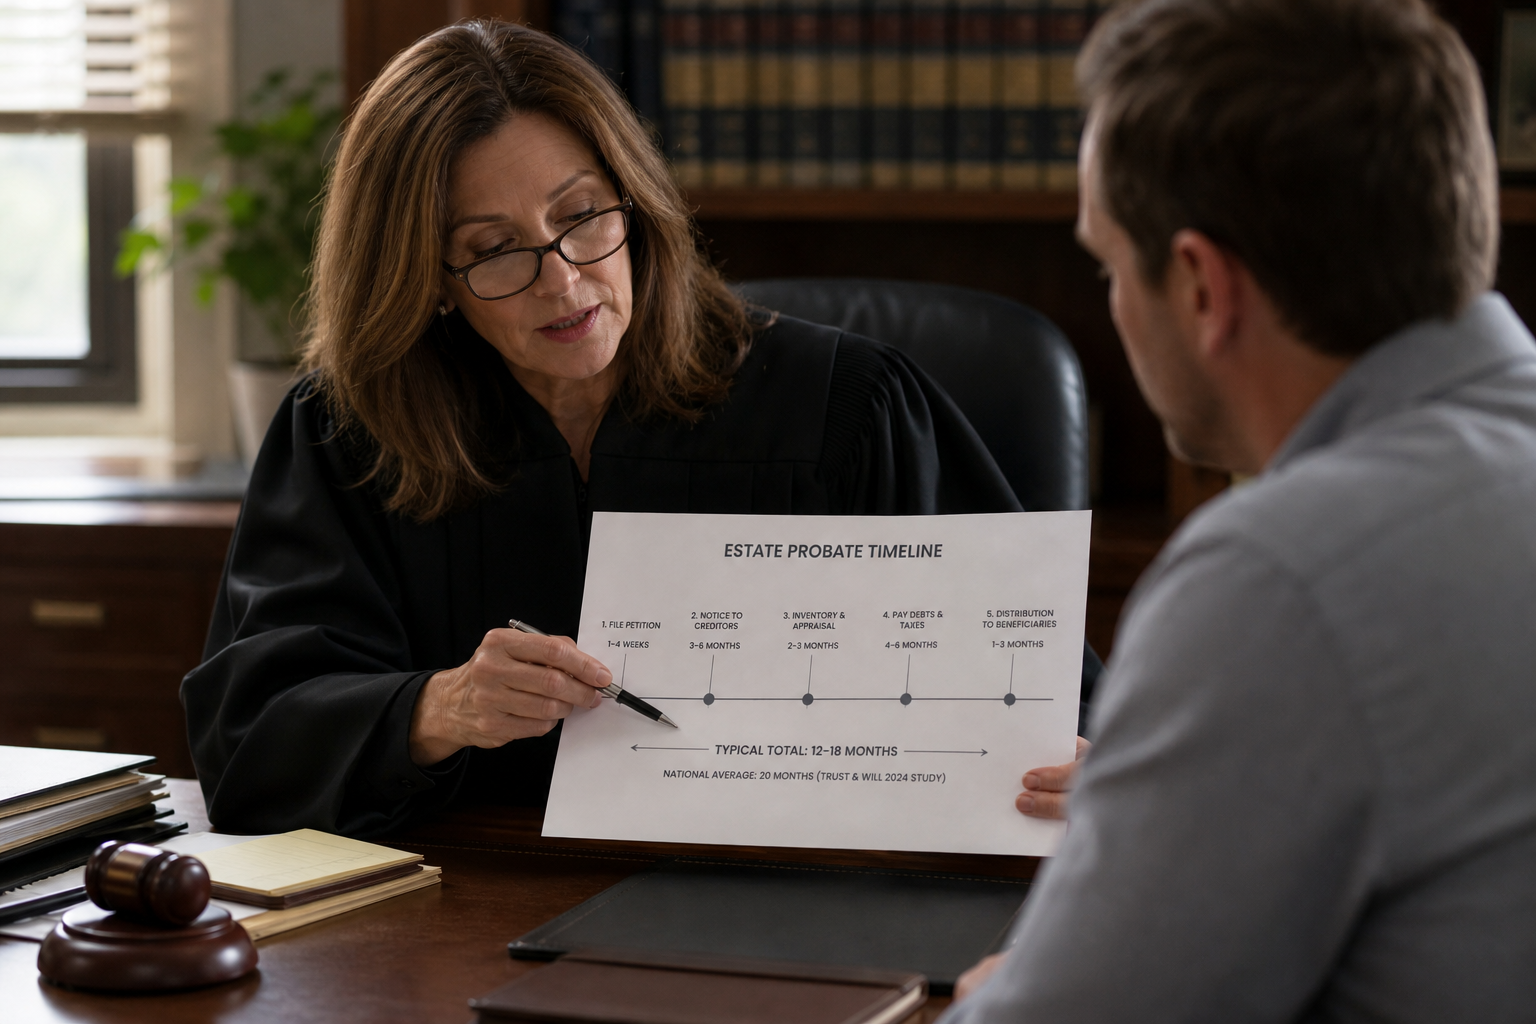
Courts can also remove you as executor, replacing you with a professional administrator whose fees reduce the estate, and you may forfeit any executor commission earned. Fraud, theft, or deliberate self-dealing can bring civil or criminal exposure. A Trust & Will 2024 study found the national average probate timeline is 20 months, and contested proceedings from misconduct can stretch beyond that.
Data cited November 2026. Information subject to change.
The Audit Trail Requirement: Documenting Every Decision
Every decision you make as executor needs a paper trail. Courts review your records, not your intentions, and gaps read as evidence of a problem rather than poor organization. These recordkeeping habits mirror the trustee duties and responsibilities expected of anyone managing assets for others. Keep records across four core categories:
- Financial transactions: bank statements, canceled checks, receipts
- Asset management decisions: appraisals, sale agreements, written bids
- Creditor claims: accept or reject decisions, proof of payment
- Beneficiary communications: dates, method, and content of updates
The standard is what a reasonably prudent person would have documented. If a beneficiary challenges a decision, your file is your defense.
How Alix Handles the Administrative Work Behind These Duties

Every fiduciary duty covered here carries a practical layer, and Alix's specialists take it on: appraisals and sale logistics are handled through Alix's vendor partners, which Alix coordinates for your inventory filings, tracking creditor claims such as medical bills, credit card balances, mortgage servicer notices, and utility arrears, and property coordination covering locksmith access, utility transfers, insurance continuation, and routine maintenance through vendor partners, with vendor costs paid by the estate. Based on Alix's data across client cases, estate settlement requires 600 or more hours over 18 months, roughly 15 full-time work weeks, and that's the workload you hand off.
Alix's estate settlement specialists handle more than 150 administrative tasks that don't require a law license, folding asset discovery, creditor coordination, beneficiary communication, tax filing coordination, and property coordination into one process. An attorney from Alix's network handles standard probate legal work as part of one transparent, estate-funded fee whether or not your state requires an attorney, so you don't need to source your own, though you can bring your own if you prefer, with those fees handled separately. That fee covers most of the work, but court filing fees, legal notice publication, and vendor costs like appraisals and tax prep are typically paid by the estate, and back taxes or legal work beyond standard probate may fall outside it. Family disagreement alone doesn't rule an estate out, but Alix can't begin while there is legal contention (anything filed with the court, an attorney hired over the dispute, or someone saying they plan to sue, contest the will, or challenge who is in charge) until it is fully resolved; network attorneys don't handle contested matters or litigation. Alix serves complex probate and trust estates, and a very small, simple estate is a fit only if you're comfortable paying Alix's standard fee for that work.
If you're ready to stop managing this piecemeal, start your Alix onboarding.
FAQs
Can a beneficiary buy estate property below market value if the rest of the family agrees?
Generally not, even with family agreement. Your duty runs to all beneficiaries equally, and a below-market sale harms everyone who isn't the buyer. Get a credentialed appraisal and require market value, or the other beneficiaries can pursue you personally for the shortfall.
What are executor responsibilities for documenting decisions during estate administration?
Keep records of every financial transaction, asset decision, creditor claim, and beneficiary communication from appointment until the estate closes. Courts review records, not intentions. Save bank statements, appraisals, sale agreements, creditor accept-or-reject decisions, and dated notes on beneficiary updates.
What are the fiduciary duties of an executor when a creditor surfaces after assets have already been distributed?
If you distribute assets before the creditor claim window closes and a valid debt surfaces afterward, you can be held personally liable for the shortfall. Creditors come before beneficiaries by law. Wait until the window expires and debts are paid before distributing.
Final Thoughts on Carrying Out Your Executor Fiduciary Duties
Every one of the executor fiduciary duties covered here comes back to the same thing: put the estate and its beneficiaries first, and keep records that prove you did. The risk is personal and real, but so is the path through it. A clear sequence, consistent documentation, and timely communication with beneficiaries cover most of what courts look for. Start your Alix onboarding and hand the administrative work to an Alix specialist from day one.

Related resources