A lot of executors spend the first few weeks worrying that family members will somehow end up on the hook for a parent's credit card debt or old medical bills. That fear is mostly misplaced, but the real deadline risk sits somewhere else entirely. The statute of limitations on debt after death in California is strict, and if you distribute assets before the creditor window closes, you could be the one left personally liable.
Key Takeaways:
- CCP § 366.2 gives creditors 1 year from death to sue, replacing any longer clock from when the person was alive.
- Heirs don't owe a deceased person's debts unless they co-signed, held a joint account, or are a surviving spouse under community property rules.
- Distribute assets only after the creditor-claim window closes, because paying beneficiaries early can leave you personally liable.
- Under federal debt collection rules, collectors should direct estate debt discussions to the executor or person handling the estate, and California's SB 1286 extended Rosenthal Act protections to certain commercial debts of $500,000 or less as of July 1, 2025.
- Alix is a human-led estate settlement service that folds creditor work into one coordinated settlement, with specialists tracking bills and negotiating unsecured debts and a network attorney handling formal creditor notices and claim responses. Alix's one transparent fee is paid from the estate and typically covers most of this work, but it doesn't usually cover court filing fees or legal notice publication costs, which the estate pays.
What Happens to Debt When Someone Dies in California
Debt doesn't disappear when someone dies. In California, it becomes an obligation of the estate, paid from assets left behind before anything goes to beneficiaries.
Many executors worry about inheriting a parent's debt. As the Consumer Financial Protection Bureau notes, you are generally not responsible for someone else's debt. If the estate runs out of money, creditors simply don't get paid in full, and heirs don't cover the difference personally, unless you co-signed a loan, held a joint account, or are a surviving spouse in a community property state like California, covered later in this guide.
As executor, your job is to identify debts, notify creditors, and pay valid claims in the right order before distributing anything to beneficiaries.
California's Two Parallel Timelines: CCP § 366.2 and the Probate Claims Window
California runs two separate clocks on creditor rights after a death, and knowing which one applies is where executors most often get tripped up.
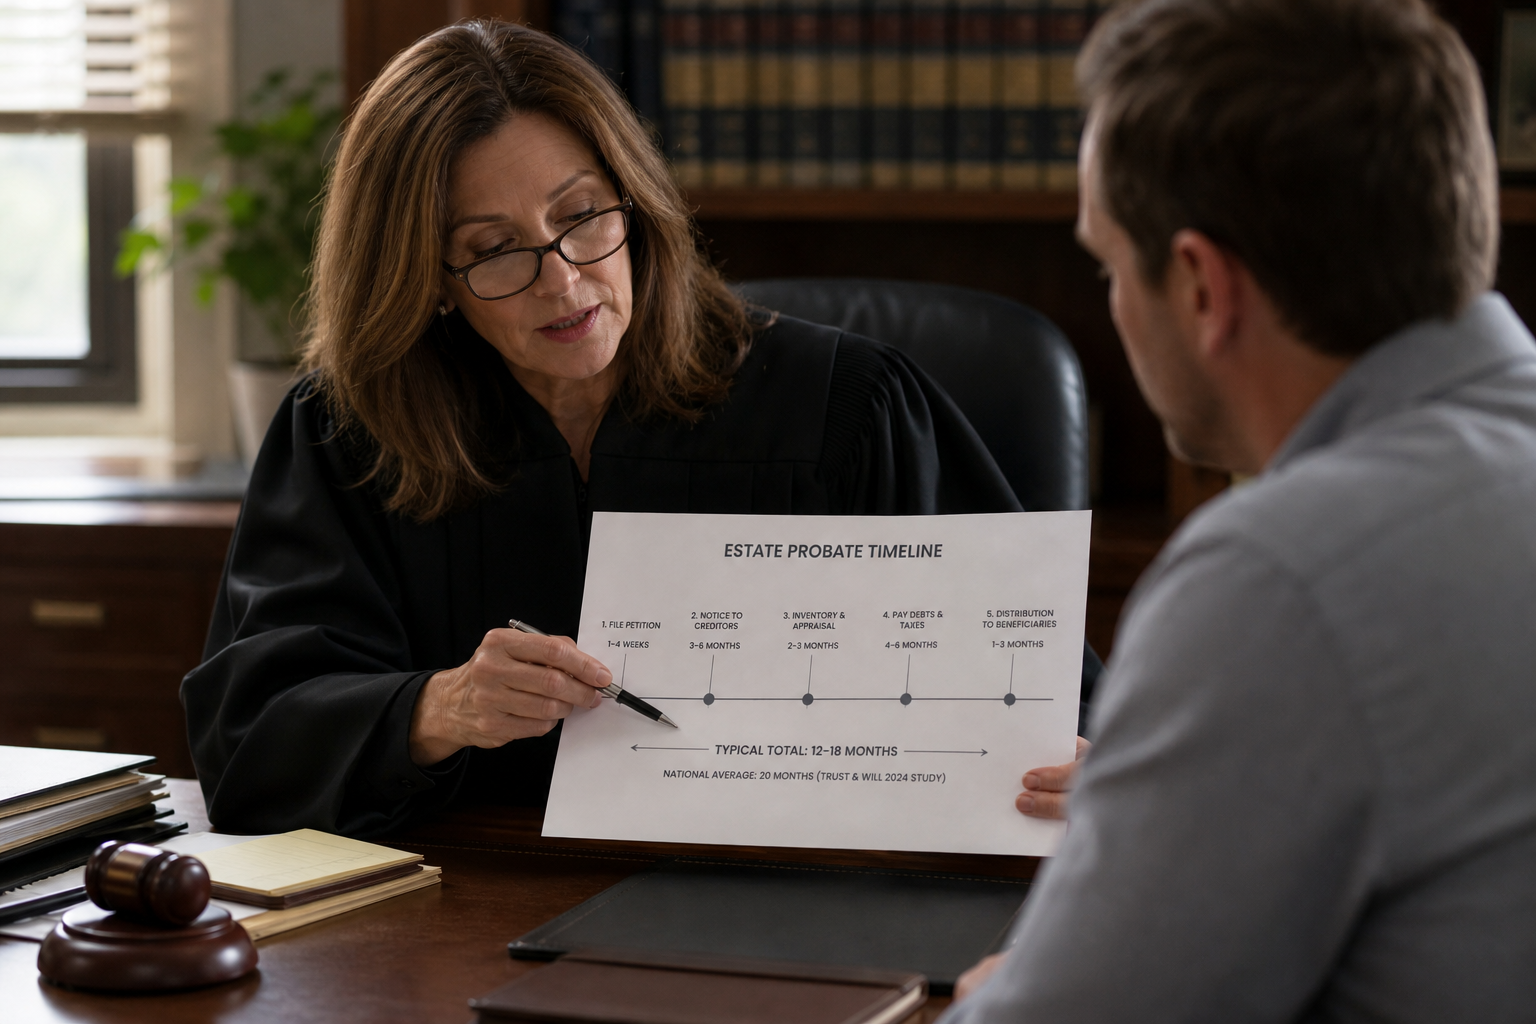
The first is California Code of Civil Procedure § 366.2: a strict one-year limit from the date of death for any creditor to sue the estate. It replaces whatever limit applied while the person was alive. As Wolf Group L.A. explains in their analysis of creditor claims, this bar is absolute in most cases. A credit card debt with four years left on its normal clock is gone if not pursued within one year of death.
The second clock is the probate claims window. Once the court issues your letters, creditors typically get a shorter window to file formal claims, and it never extends the one-year ceiling.
In practice, the two interact this way:
- The one-year bar applies even if probate has not been opened.
- The probate claims deadline can cut creditors off before the one-year mark, but never push a claim past it.
How the Probate Notice to Creditors Process Works in California
California's notice to creditors process runs in two parts. Before the court appoints you as executor, a Notice of Petition to Administer Estate must be published in a local newspaper in the decedent's county. Once appointed, you mail a formal Notice of Administration to Creditors (Judicial Council form DE-157) to any creditors you know about, typically within four months of your letters being issued, or within 30 days of learning about a creditor after that.
Creditors must then file claims by whichever deadline is later under California Probate Code § 9100: four months after the court first issues your letters, or 60 days from the mailed notice. Missing this deadline generally bars a creditor, but only if you followed the process correctly. Skipping publication, mailing late, or missing known creditors can leave the estate exposed after you've distributed assets, and recovering those funds from beneficiaries is its own legal problem.
California's Debt Statute of Limitations by Debt Type
California's statute of limitations depends on the debt type. These limits applied while the decedent was alive, before death triggered the one-year rule under CCP § 366.2.
| Debt Type | California Statute of Limitations |
|---|---|
| Written contracts (credit cards, personal loans) | 4 years (CCP § 337) |
| Oral contracts | 2 years (CCP § 339) |
| Open-book accounts | 4 years (CCP § 337) |
For credit card debt, the four-year clock typically starts at the first missed payment. Once a person dies, CCP § 366.2 replaces any remaining time with a one-year ceiling from the date of death.
Data cited November 2026. Information subject to change.
What Can Restart or Pause the Statute of Limitations in California
In California, a payment or a signed written acknowledgment or promise to pay can restart the four-year clock, but generally only while that clock is still running:
- A payment made before the four-year period runs out typically restarts the period from that payment date.
- Once a consumer debt is already time-barred, California law (CCP § 337, as amended by AB 1526) generally bars suit and says a later payment does not revive or extend the limitations period.
After death, the CCP § 366.2 one-year period does not restart, and the estate's personal representative cannot accidentally revive a time-barred debt.
When the Clock Pauses Instead of Resets
California law can toll the pre-death limitations period if the debtor was absent from the state in ways that prevented service of process, but that tolling does not apply to the post-death CCP § 366.2 rule.
As executor, verify any claim is valid and confirm the limitation period has not run before paying it, even for estates small enough to qualify for a small estate affidavit.
Community Property Rules and Surviving Spouse Liability
California is one of nine community property states, which changes the liability math for surviving spouses in a meaningful way.

Debts incurred during a marriage are generally community debts, and creditors can pursue community property to satisfy them, including the surviving spouse's half. Under California Probate Code § 13550, a surviving spouse who takes property without estate administration can be held personally liable for the deceased spouse's debts.
That liability has a ceiling. Under Probate Code § 13551, exposure cannot exceed the fair market value at death, minus liens, of the non-exempt community and quasi-community property the spouse takes without administration, plus any of the decedent's separate property that passes to them without administration. The surviving spouse's own separate property falls outside that cap.
Joint account holders are liable regardless of community property rules. Authorized users are not, a distinction the CFPB draws explicitly. If unsure which applies, review the account agreement before paying.
What Happens When the Estate Has No Money to Pay Debts
An insolvent estate owes more than it has. California law sets a priority order for paying claims, and creditors at the bottom may not get paid.

Under California Probate Code § 11420, after debts with preference under federal or state law (such as certain taxes), the priority order generally runs like this:
- Expenses of administration, including executor and attorney fees
- Secured debts, up to the value of the property securing them
- Funeral expenses
- Expenses of the last illness
- Family allowance
- Certain wage claims
- General unsecured debts (credit cards, medical bills, personal loans, and the unsecured part of secured debts)
As the CFPB notes, an estate with no money or property left generally leaves the debt unpaid. Heirs are not responsible for the shortfall unless they co-signed the debt or held a joint account; collectors pressuring beneficiaries to pay from personal funds are acting outside what California law permits. Pay beneficiaries before the creditor-claim window closes, and a valid creditor later comes forward, and you as executor can face personal liability. Pay valid claims from the estate account first, then distribute what remains.
Known vs. Unknown Creditors and Your Obligations as Executor
California law treats known and unknown creditors differently, with real consequences for you as executor.
Known creditors, those you are aware of or can reasonably identify from the decedent's financial records, must receive direct written notice. Mailing a formal Notice to Creditors is not optional: skipping it leaves that creditor's claim window open longer, since a known creditor who never got mailed notice can often still file a late claim under California Probate Code § 9103.
Unknown creditors receive constructive notice through newspaper publication. If a creditor had no prior relationship with the decedent and no way to know they were owed money, publication satisfies your obligation to them.
The harder category is what California courts call "reasonably ascertainable" creditors, such as a medical provider or utility company listed in the decedent's records. You may not know about them personally, but reasonable diligence through bank statements, billing records, and mail would have found them, work that typically happens alongside tasks like getting an EIN for an estate account, which you can only request after the probate court appoints you as executor or administrator. Failing to find and notify such a creditor can expose you to personal liability if assets were distributed before their claim was paid.
What Happens When Creditors Miss the Deadline
When a creditor misses the probate claims window or the one-year CCP § 366.2 deadline, the claim is barred and the estate owes nothing on it. California courts treat the § 366.2 deadline as an absolute bar, not a soft guideline, so a creditor who slept on a valid debt loses it.
A few narrow exceptions exist. Some creditors argue equitable estoppel, claiming the executor's conduct kept them from filing on time, but courts allow this only where the estate actively misled the creditor. Government tax claims and some federally backed obligations can also fall outside the § 366.2 framework, so consult the probate attorney handling your California formal probate before treating any such claim as expired.
Debt Collector Rules After a Death: Your Rights as Executor
Once a collector knows the debtor has died, federal rules generally limit them to discussing the debt with you as executor (or whoever has authority over the estate) and a surviving spouse, not other family members.
- Collectors cannot harass, threaten, or use deceptive tactics to pressure you into paying debts the estate doesn't owe.
- If you dispute the debt in writing within the 30-day validation period, the collector must pause collection until it verifies the debt.
- Collectors cannot sue on a time-barred debt. As the California Attorney General's office notes, ignoring contact can result in a default judgment, so respond in writing to dispute or request validation.
California goes further than federal law: SB 1286 expanded the Rosenthal Act to cover certain commercial debts up to $500,000 entered into, renewed, sold, or assigned on or after July 1, 2025. A non-executor relative with no joint liability can decline to discuss the debt and direct the collector to the estate representative.
How Alix Handles Creditor and Debt Coordination as Part of Estate Settlement

Creditor coordination is one of the most deadline-sensitive parts of estate settlement, and Alix handles it as part of one coordinated process. As a human-led estate settlement service, Alix pairs estate settlement specialists, who handle more than 150 administrative tasks across a settlement, with an attorney from Alix's network. The specialists organize and track medical bills, credit card balances, mortgage servicer notices, and utility arrears, and the attorney handles the formal creditor notices and claim responses.
On unsecured debts such as credit cards and medical bills, Alix negotiates with creditors on the estate's behalf, averaging a 49% reduction based on Alix's data across client cases. Alix's one transparent fee, paid from the estate's assets once they're secured, covers Alix's service, including the network attorney's standard probate and settlement work. The fee typically doesn't cover court filing fees, legal notice publication costs such as the creditor notice publication described above, or vendor costs, which the estate usually pays. Alix's network attorneys don't handle contested matters or litigation, and Alix begins only after any dispute over the will or who is in charge is fully resolved. If you already have your own attorney, that works too. Attorney fees for that work, or for legal needs beyond standard probate such as back-tax matters, are handled separately.
The CCP § 366.2 one-year bar, the probate claims window, and known versus unknown creditor notices all sit inside that one process, worked by your Alix team, so those deadlines come off your plate.
FAQs
How are creditor claims against a California estate validated, disputed, or negotiated, including old claims near or past the statute of limitations?
You can request written debt validation before paying any claim, and you don't have to pay one that misses the probate claims window or the CCP § 366.2 ceiling. Valid unsecured debts can often be negotiated, and weakly documented claims can be disputed or reduced.
What can restart the debt statute of limitations in California before someone dies?
A payment, or a signed written acknowledgment or promise to pay, can restart the four-year clock on a written contract while that clock is still running. Once a consumer debt is already time-barred, California law generally says a later payment does not revive it. After death, CCP § 366.2 replaces the remaining clock with a one-year ceiling from the date of death.
What is the statute of limitations on credit card debt in California for a deceased person's estate, and does it differ from the general rule?
For a living debtor, the limit on credit card debt is four years from the first missed payment under CCP § 337. After death, CCP § 366.2 replaces it with a one-year limit from the date of death, however much time was left.
Final Thoughts on What Executors Need to Know About Estate Debt in California
The statute of limitations on debt after death in California is strict, the deadlines are short, and the personal liability exposure for getting the order wrong is real. Identify every valid creditor, follow the notice process, pay claims in priority order, then distribute what remains. Most creditors who miss the window lose their claim, but that protection only holds if the process was run correctly. To hand the creditor process to Alix's specialists and network attorney as part of one coordinated settlement, start your Alix onboarding.

Related resources