Inheritance Tax vs Estate Tax: What Executors Owe in Each State
Compare estate tax, paid by an estate, with inheritance tax, paid by heirs. See 2026 federal thresholds, state taxes, deadlines, and executor responsibilities.
When you're sorting out inheritance tax vs estate tax as executor, the difference catches a lot of people off guard. One bill comes out of the estate before anything is distributed. The other lands on each beneficiary individually after they receive their share. Knowing which one you're dealing with, and in which state, is what tells you who files, who pays, and when.
Key Takeaways
Estate tax hits the estate before any distributions go out; inheritance tax bills each beneficiary based on what they receive.
There is no federal inheritance tax. The federal estate tax exemption is $15,000,000 per person, with Form 706 due 9 months after the date of death.
Thirteen jurisdictions levy a state estate tax, with thresholds as low as $1,000,000 in Oregon, well below the federal exemption.
Five states levy an inheritance tax in 2026: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Maryland imposes both taxes.
Pennsylvania has no estate-size threshold, so even small estates can owe inheritance tax. Paying within 3 months of the date of death earns a 5% discount, and the tax becomes delinquent after 9 months.
As executor, it's generally safest to hold distributions until estate tax and any inheritance tax are calculated and paid, since some jurisdictions can hold a fiduciary responsible for unpaid tax after assets go out. Confirm the rule for your state with a tax professional or attorney.
Estate Tax vs Inheritance Tax: The Estate Pays One, the Heir Pays the Other
Estate tax and inheritance tax work differently and land on different people.
An estate tax is charged against the estate itself, before anything goes to your beneficiaries. You pay it from estate funds during settlement. An inheritance tax is charged to each beneficiary based on what they receive, with the rate typically tied to how closely related they were to the person who died.
Here is a concrete example. Say you're settling a $500,000 estate. If the state imposes an estate tax, the estate itself owes a percentage of that $500,000 before a single dollar is distributed. If the state imposes an inheritance tax, a sibling who inherits $100,000 might owe 12%, while a child inheriting the same sum might owe 4.5% or nothing at all.
For you as executor, an estate tax is your filing and payment obligation. An inheritance tax legally falls on the beneficiary, though in some states, such as Pennsylvania, the executor often handles payment before distribution. The Who Pays section below covers how that works.
Federal Estate Tax Exemption 2026 and the Estate Tax Return (Form 706)
Most estates won't owe federal estate tax. The Working Families Tax Cuts Act, signed into law on July 4, 2025, raised the federal estate tax exemption to $15,000,000 per person for deaths in 2026. If the gross estate falls below that threshold, no federal estate tax return is required and no tax is owed.
There is also no federal inheritance tax. The federal government taxes large estates once, at the estate level, before distribution. Whether beneficiaries owe income tax on what they receive is a separate question, covered in Alix's separate guide to whether estate distributions are taxable, so this guide stays on estate and inheritance tax.
You must file Form 706 (United States Estate Tax Return) once the gross estate plus adjusted taxable gifts exceeds the basic exclusion amount, $15,000,000 for 2026 deaths. The return is due 9 months after the date of death. Form 4768 can extend the filing deadline by 6 months, but any tax owed is still due at the 9-month mark. The top federal rate is 40%. There is also a portability point worth knowing: even when no tax is due, a surviving spouse can only receive the unused exclusion if the executor files a complete, timely Form 706 that elects portability, per the Form 706 instructions. If the estate was not otherwise required to file, meaning it fell under the filing threshold, and that deadline was missed, Rev. Proc. 2022-32 allows a portability-only return on or before the fifth anniversary of the date of death. Given the complexity of a Form 706 filing, working with a tax professional or estate attorney is worth the time, and reviewing taxes and final accounting obligations early can help you stay organized.
States with Estate Tax: 2026 Exemption Thresholds
Twelve states plus Washington D.C. (13 jurisdictions total) levy their own estate tax in 2026. That matters to you as executor because state thresholds are far lower than the federal $15 million exemption, meaning an estate that owes nothing federally can still owe state estate tax. As with the federal tax, the estate pays before any distributions go out.
Each state's revenue office publishes its own threshold, and the figures below come from those official pages for deaths in 2026. They range from $1 million in Oregon up to $15 million in Connecticut. Some states test the gross estate and others the taxable estate, so confirm the filing test with the state before you rely on a figure.
State
Exemption or Filing Threshold (2026 Deaths)
Official Source
Connecticut
$15,000,000
Hawaii
$5,490,000
Illinois
$4,000,000
Illinois Attorney General estate taxes
Maine
$7,160,000
Maine Revenue Services Form 706ME
Maryland
$5,000,000
Maryland Comptroller estate tax return
Massachusetts
$2,000,000
Minnesota
$3,000,000
Minnesota estate tax filing requirement
New York
$7,350,000
New York basic exclusion amount
Oregon
$1,000,000 (gross estate filing threshold)
Oregon DOR estate transfer tax
Rhode Island
$1,838,056
RI Division of Taxation advisory
Vermont
$5,000,000
Vermont Department of Taxes estate tax
Washington
$3,076,000 (deaths January 1 to June 30, 2026); $3,000,000 (deaths on or after July 1, 2026)
Washington D.C.
$4,988,400
Oregon's $1 million threshold is the lowest in the table and is measured against the gross estate, so a home plus a retirement account can cross it. New York has its own threshold rules, which our guide to the New York estate tax cliff walks through.
Data cited November 2026. Information subject to change.
Inheritance Tax by State: Which States Have Inheritance Tax
The states with inheritance tax in 2026 are Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Iowa's inheritance tax is fully repealed for deaths on or after January 1, 2025.
In every one of these states, surviving spouses pay nothing. Children are either fully exempt or taxed at low rates. Steeper rates apply to more distant relatives and unrelated heirs. Whether a state's inheritance tax applies generally depends on the decedent's domicile and where the property is located (situs) under that state's law, plus the beneficiary's relationship and any exemptions, not on where the beneficiary lives.
State
Spouse
Children/Lineal
Siblings
Others
Official Source
Kentucky
0%
0%
0% (Class A)
4% to 16% after a $1,000 exemption (Class B, such as nieces, nephews, aunts and uncles); 6% to 16% after a $500 exemption (Class C, all others)
Kentucky Department of Revenue
Maryland
0%
0%
0%
10% (nieces, nephews, aunts, uncles, cousins and unrelated heirs)
Nebraska
0%
1% above $100,000
1% above $100,000
11% above $40,000 (aunts, uncles, nieces, nephews and their descendants); 15% above $25,000 (all others)
Nebraska Revised Statute 77-2004
New Jersey
0%
0%
11% to 16% after the first $25,000 (Class C, siblings and a child's spouse)
15% up to $700,000, 16% above (Class D)
Pennsylvania
0%
4.5%
12%
15%
Pennsylvania Department of Revenue
Each state sets its own exemption amounts, filing deadlines, and relationship classes, so confirm the details with that state's revenue office. Pennsylvania has no estate-size threshold, so even small estates can owe tax, aside from narrow exemptions set by the Department of Revenue. Under Nebraska Revised Statutes 77-2004 through 77-2006, property passing to a beneficiary under age 22 is not subject to Nebraska inheritance tax. The sections below cover Pennsylvania in more detail, with notes on the other four states where relevant.
Data cited November 2026. Information subject to change.
Pennsylvania Inheritance Tax: What Executors Need to Know
Pennsylvania sits in a category of its own among inheritance tax states. It has no state estate tax, only an inheritance tax, and that tax applies regardless of estate size. There is no estate-size threshold to clear first, though specific transfers (such as to a spouse or charity) are exempt. A $40,000 estate can owe Pennsylvania inheritance tax just as surely as a $4 million one.
The Pennsylvania Department of Revenue sets rates by the beneficiary's relationship to the decedent:
0% on transfers to a surviving spouse, or to a parent from a child age 21 or younger
4.5% on transfers to direct descendants and lineal heirs
12% on transfers to siblings
15% on transfers to other heirs, except charities, exempt institutions and exempt government entities
Transfers to qualifying charities and government entities are exempt, as is jointly owned property between spouses. You'll typically need an EIN for the estate account to manage estate funds, so confirm the requirements with the IRS or a tax professional.
As executor, filing and payment typically fall on you. Pennsylvania inheritance tax is due at the date of death and becomes delinquent 9 months after that date, but pay within 3 months of death and the state allows a 5% discount on the tax owed. That discount is worth planning around, especially where the 12% and 15% rates apply.
States with Both an Estate Tax and an Inheritance Tax
Maryland is the only state that currently imposes both taxes. That means a Maryland estate can owe a state estate tax before any distributions go out, and a beneficiary may separately owe inheritance tax on what they receive. The two are coordinated rather than simply stacked: per the Maryland Comptroller, inheritance tax paid to the Register of Wills is subtracted from the gross Maryland estate tax before the estate tax bill is calculated.
Per the Maryland Register of Wills, a spouse, children and other lineal descendants, a child's spouse, stepchildren, parents, grandparents, and siblings are exempt from inheritance tax. Other beneficiaries, such as nieces, nephews, aunts, uncles, cousins, and unrelated heirs, generally pay 10%. For those beneficiaries, the estate may first owe Maryland estate tax, and their share may then owe inheritance tax, with the inheritance tax credited against the estate tax as described above.
Every other state covered here lands in one column or the other. Massachusetts, Oregon, and Washington levy an estate tax with no inheritance tax. Pennsylvania, New Jersey, Kentucky, and Nebraska levy an inheritance tax with no estate tax. Your filing obligations differ considerably depending on which regime applies, so verify current rules with the relevant state revenue authority before filing anything.
States with No Inheritance Tax or Estate Tax
Most states impose no state-level estate or inheritance tax at all. The majority of the 50 states fall into this category, so a decedent domiciled there typically leaves beneficiaries without a state death tax reducing the estate beforehand or arriving as a separate bill afterward. That said, owning real estate or other property located in a state that does levy one of these taxes can still trigger a filing obligation there under that state's own rules, regardless of where the decedent lived.
Federal estate tax still applies wherever your loved one lived. If the gross estate exceeds the $15,000,000 federal exemption for 2026 deaths, Form 706 is due 9 months after the date of death.
For executors in states like Florida, Texas, California, or Colorado, the decedent's home state typically adds no estate or inheritance tax, though you'll still need to manage an estate account for federal filings and distributions. The death-tax work is usually federal only, unless property sits in another state that taxes it, and for most estates, even the federal threshold won't be crossed.
Who Pays Estate Tax and Who Pays Inheritance Tax
For estate taxes, federal or state, the executor or personal representative typically files the return and pays the bill from estate funds, and distributions wait until the tax is settled. Distributing before the tax is settled can expose a fiduciary to liability for unpaid tax in some situations, and the rules differ by jurisdiction, so check with your tax professional or attorney before distributing.
Inheritance tax is generally owed on each beneficiary's share. In some states, such as Pennsylvania, the personal representative files the inheritance tax return, and the tax is often paid from the estate or withheld from a share before distribution. Who files and pays differs by state and by the will's terms, so confirm the process with that state's revenue office.
One practical wrinkle worth knowing: some inheritance tax states may require a tax waiver or release before certain banks, brokerages, or transfer agents will release assets held in your loved one's name. Whether one is needed depends on the state, the type of asset, and the beneficiary's relationship to the decedent. Ask that state's revenue office early, since you may need to start that process before you can move money at all, so it's worth adding this step to your executor checklist.
What Assets Are Subject to Each Tax
What counts as a taxable asset depends on which tax you're dealing with and which state you're in.
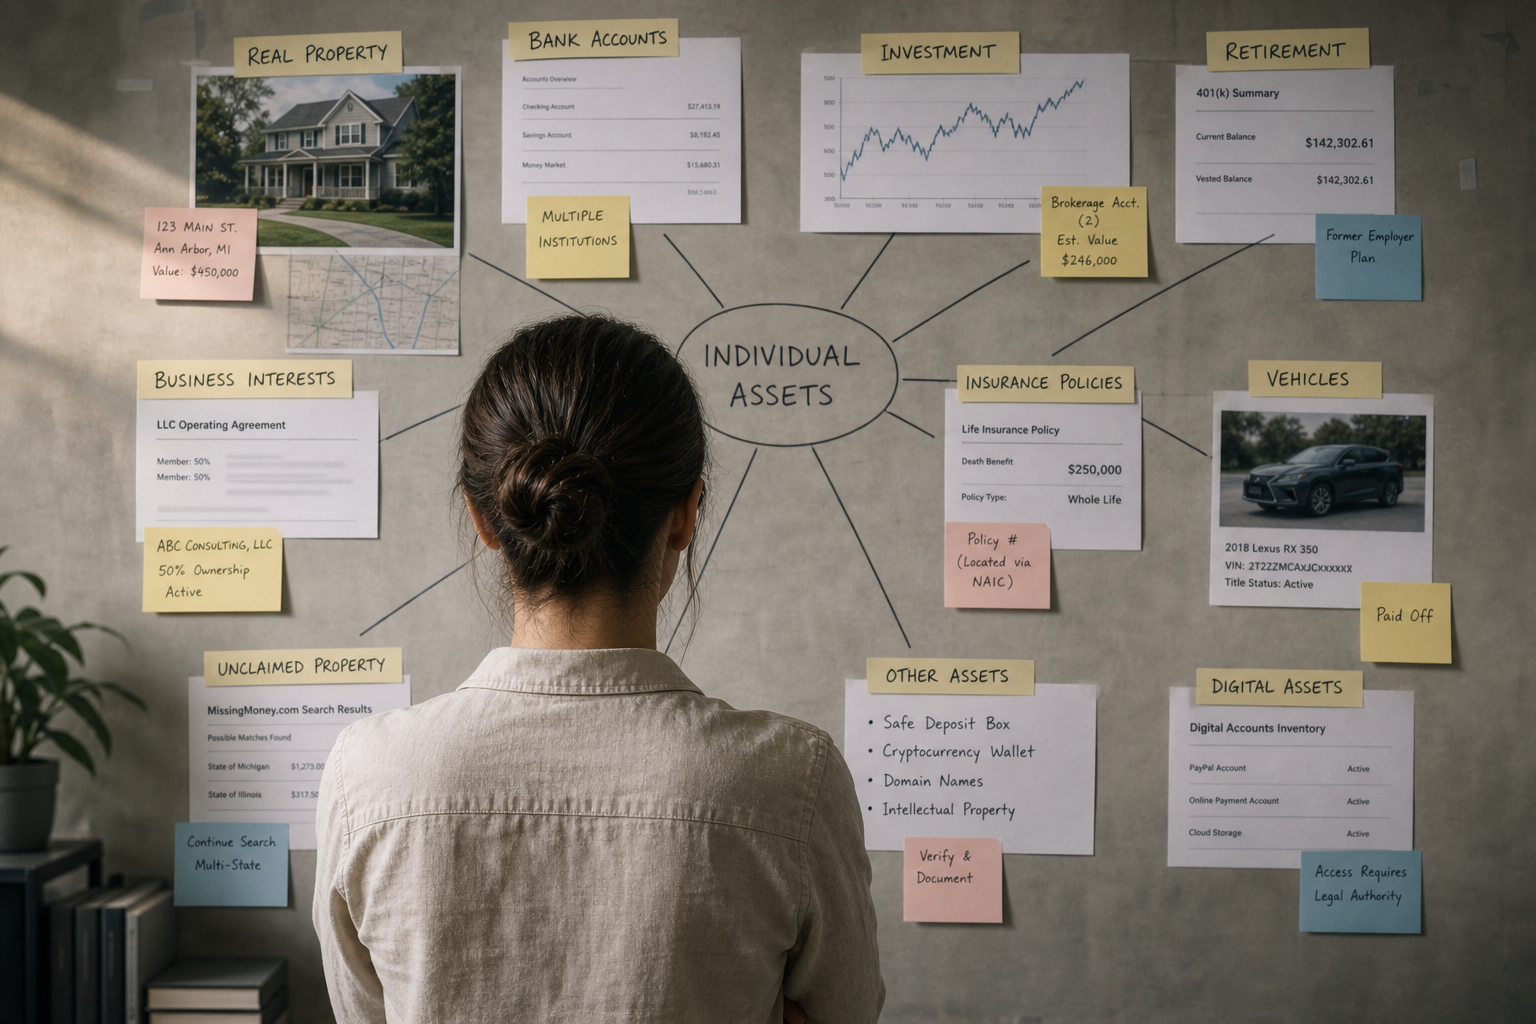
For federal estate tax, the IRS casts a wide net. The gross estate generally includes everything the decedent owned or controlled at death: real property, bank and brokerage accounts, retirement accounts, business interests, personal property, and life insurance proceeds where the decedent held incidents of ownership over the policy. The key word is "controlled." Assets held in certain trusts, or where the decedent retained rights over the proceeds, can still land in the gross estate even if they never touched probate.
Inheritance tax states focus on a simpler question: what did each beneficiary actually receive? The tax attaches to the transferred amount, not the estate's total value. A beneficiary who inherits $80,000 from a $1.2 million estate is generally taxed on that $80,000, subject to that state's exemptions and rate class.
A common point of confusion involves assets that pass outside of probate. Jointly held property with right of survivorship, payable-on-death accounts, and beneficiary-designated retirement accounts all transfer directly to the named recipient without going through the will. That does not make them tax-free. Many of these assets are still counted in the federal gross estate. Whether they are subject to state inheritance tax depends on the state, since some states exempt certain assets such as life insurance or specific retirement benefits.
How the Two Taxes Affect Your Timeline as Executor
Deadlines for these taxes vary by state, so check the rules where the estate is being settled before you set your own timeline. The federal estate tax return, Form 706, is due 9 months from the date of death. Pennsylvania's inheritance tax becomes delinquent on that same 9-month mark, though filing and paying within 3 months earns a 5% discount. Other states run on different clocks: Kentucky gives you 18 months to file and pay its inheritance tax, with a 5% discount if paid within 9 months, while the D.C. estate tax return is generally due 10 months after death. These deadlines run from the date of death, not from your appointment, so confirm the applicable deadline for each state where the decedent was domiciled or owned property as early as you can.
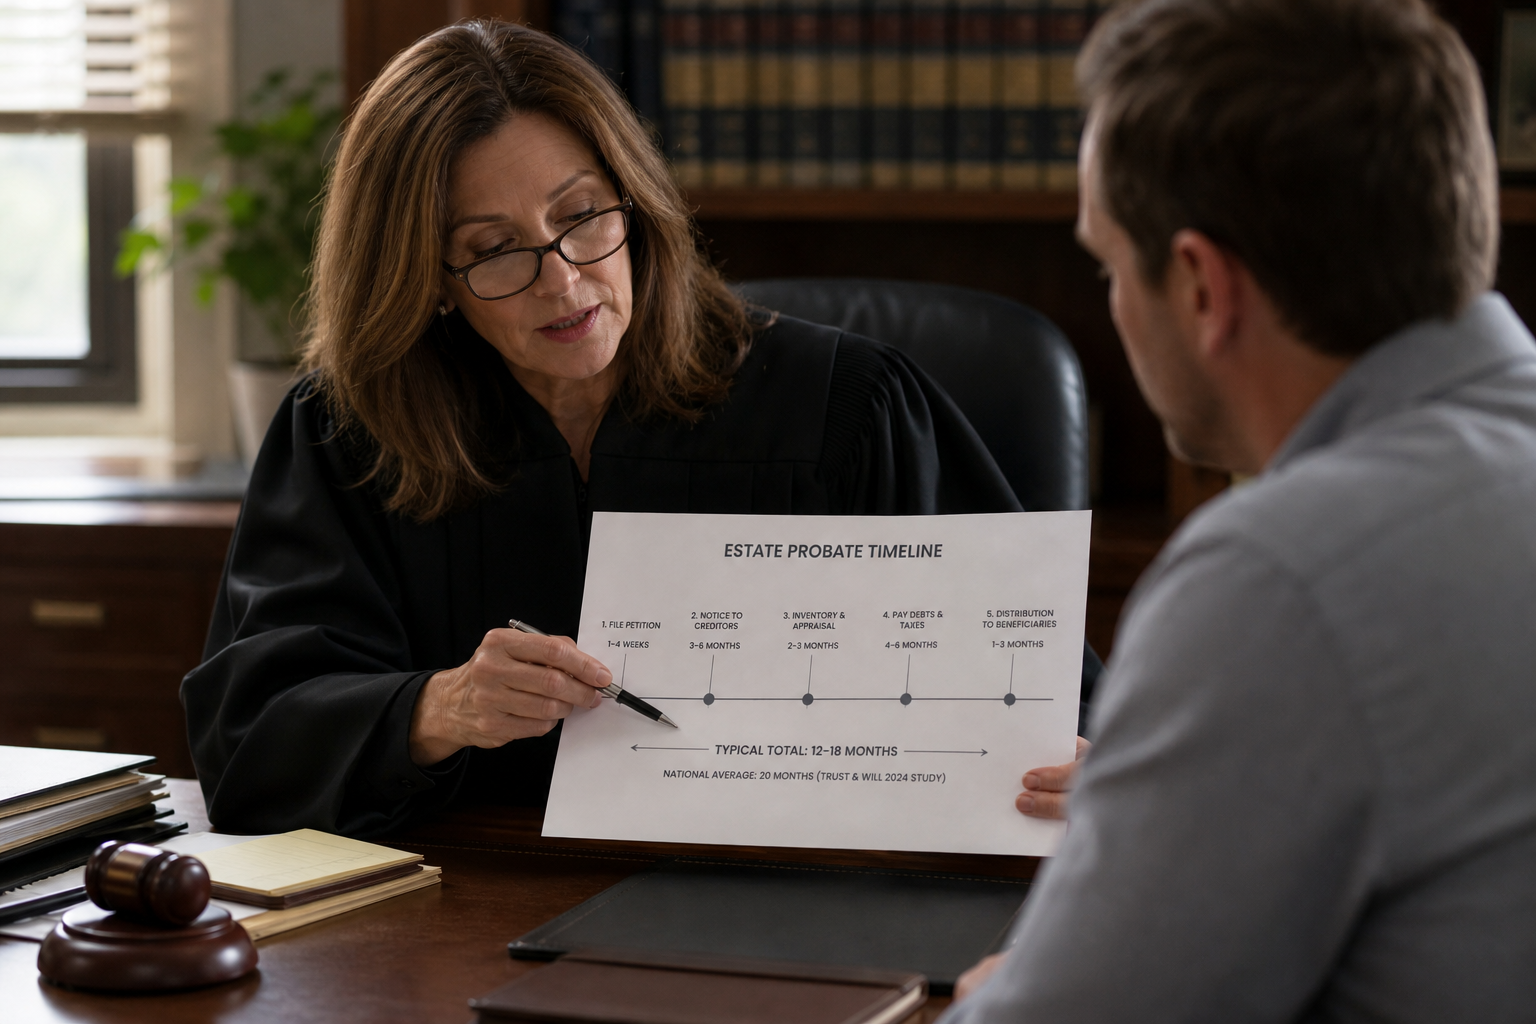
That window sounds generous until you map out what comes first. Before filing, you will usually need date-of-death values for estate assets, which can mean gathering account statements from every institution and, for assets like real estate or a business, getting a valuation. These steps often overlap with creditor claims and the rest of the work covered in our probate timeline guide, so tax filings tend to land in the middle of an active settlement.
As part of distributing assets and closing the estate, holding distributions until applicable taxes are calculated and paid is generally the cautious approach. That hold protects beneficiaries as well as you.
How Alix Helps Executors Handle Estate and Inheritance Tax Obligations
Alix's estate settlement service works alongside your tax professional or attorney to coordinate estate tax filings as part of settlement. That coordination keeps federal and state filing dates in view; for the full sequence, see our guide to settling an estate.
Final Thoughts on Estate and Inheritance Tax Obligations
The core takeaway is straightforward: know which tax applies, who pays it, and when the deadline lands before you move a single dollar. State rules vary enough that Oregon's $1 million threshold and Pennsylvania's no-floor inheritance tax can surprise even careful executors. The federal Form 706 deadline and Pennsylvania's delinquency date both fall 9 months after death, but other states, such as Kentucky, run on different clocks, and every one of those clocks starts at the date of death. Connect with an Alix specialist to work through the tax obligations specific to your estate.
FAQ
What is the difference between inheritance tax and estate tax?
Estate tax is charged against the estate itself before any distributions go out, and you typically file and pay it from estate funds during settlement. Inheritance tax is charged to each beneficiary based on what they receive, with rates that depend on their relationship to the decedent and the state involved. Who actually files and pays inheritance tax varies by state, so confirm the process where the estate is being settled.
Is there a federal inheritance tax?
No, there is no federal inheritance tax. The federal government taxes large estates once, at the estate level, through the federal estate tax, so what you receive as a beneficiary is not separately taxed by the IRS. Whether you owe anything still depends on where the decedent lived, since a state inheritance tax may apply even though no federal version exists.
Which states have inheritance tax?
Five states levy an inheritance tax in 2026: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Iowa repealed its inheritance tax for deaths on or after January 1, 2025, so it no longer applies there. In all five remaining states, surviving spouses are exempt, and rates typically rise the more distantly a beneficiary is related to the person who died. If the decedent was domiciled elsewhere, a state inheritance tax generally won't apply, unless the decedent owned property located in one of these five states, in which case that state may tax the transfer under its own rules.
Which states have both an estate tax and an inheritance tax?
Maryland is the only state that currently imposes both. Spouse, children and other lineal descendants, a child's spouse, stepchildren, parents, grandparents, and siblings are exempt from Maryland's inheritance tax. Nieces, nephews, aunts, uncles, cousins, and unrelated heirs generally pay 10%. Inheritance tax paid is credited against the Maryland estate tax, so the combined bill ends up lower than simply adding the two taxes together.
What is the federal estate tax exemption in 2026, and when is Form 706 due?
For deaths in 2026, the federal estate tax exemption is $15,000,000 per person, per the IRS. If the gross estate exceeds that threshold, you file Form 706, due 9 months after the date of death, and the top federal rate is 40% on amounts above the exemption. If the estate falls below the threshold, no federal estate tax return is required.
Who pays estate tax and who pays inheritance tax?
As executor, you typically file and pay estate tax from estate funds before any distributions go out. Inheritance tax is generally owed on each beneficiary's share; in some states the personal representative files the return, and the tax may be paid from the estate or withheld from a beneficiary's share, depending on the state and the terms of the will. Practices vary by state, so confirm the requirements with that state's revenue office before distributing.
What's the fastest way to reduce what a Pennsylvania estate owes in inheritance tax?
Pay within 3 months of the date of death, and Pennsylvania gives you a 5% discount on the tax owed. The tax becomes delinquent 9 months after death, so missing the 3-month window costs you the discount, and paying after 9 months adds interest.
104 container When you're sorting out inheritance tax vs estate tax as executor, the difference catches a lot of people off guard. One bill comes out of the estate before anything is distributed. The other lands on each beneficiary individually after they receive their share. Knowing which one you're dealing with, and in which state, is what tells you who files, who pays, and when.
Key Takeaways
Estate tax hits the estate before any distributions go out; inheritance tax bills each beneficiary based on what they receive.
There is no federal inheritance tax. The federal estate tax exemption is $15,000,000 per person, with Form 706 due 9 months after the date of death.
Thirteen jurisdictions levy a state estate tax, with thresholds as low as $1,000,000 in Oregon, well below the federal exemption.
Five states levy an inheritance tax in 2026: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Maryland imposes both taxes.
Pennsylvania has no estate-size threshold, so even small estates can owe inheritance tax. Paying within 3 months of the date of death earns a 5% discount, and the tax becomes delinquent after 9 months.
As executor, it's generally safest to hold distributions until estate tax and any inheritance tax are calculated and paid, since some jurisdictions can hold a fiduciary responsible for unpaid tax after assets go out. Confirm the rule for your state with a tax professional or attorney.
Estate Tax vs Inheritance Tax: The Estate Pays One, the Heir Pays the Other
Estate tax and inheritance tax work differently and land on different people.
An estate tax is charged against the estate itself, before anything goes to your beneficiaries. You pay it from estate funds during settlement. An inheritance tax is charged to each beneficiary based on what they receive, with the rate typically tied to how closely related they were to the person who died.
Here is a concrete example. Say you're settling a $500,000 estate. If the state imposes an estate tax, the estate itself owes a percentage of that $500,000 before a single dollar is distributed. If the state imposes an inheritance tax, a sibling who inherits $100,000 might owe 12%, while a child inheriting the same sum might owe 4.5% or nothing at all.
For you as executor, an estate tax is your filing and payment obligation. An inheritance tax legally falls on the beneficiary, though in some states, such as Pennsylvania, the executor often handles payment before distribution. The Who Pays section below covers how that works.
Federal Estate Tax Exemption 2026 and the Estate Tax Return (Form 706)
Most estates won't owe federal estate tax. The Working Families Tax Cuts Act, signed into law on July 4, 2025, raised the federal estate tax exemption to $15,000,000 per person for deaths in 2026. If the gross estate falls below that threshold, no federal estate tax return is required and no tax is owed.
There is also no federal inheritance tax. The federal government taxes large estates once, at the estate level, before distribution. Whether beneficiaries owe income tax on what they receive is a separate question, covered in Alix's separate guide to whether estate distributions are taxable, so this guide stays on estate and inheritance tax.
You must file Form 706 (United States Estate Tax Return) once the gross estate plus adjusted taxable gifts exceeds the basic exclusion amount, $15,000,000 for 2026 deaths. The return is due 9 months after the date of death. Form 4768 can extend the filing deadline by 6 months, but any tax owed is still due at the 9-month mark. The top federal rate is 40%. There is also a portability point worth knowing: even when no tax is due, a surviving spouse can only receive the unused exclusion if the executor files a complete, timely Form 706 that elects portability, per the Form 706 instructions. If the estate was not otherwise required to file, meaning it fell under the filing threshold, and that deadline was missed, Rev. Proc. 2022-32 allows a portability-only return on or before the fifth anniversary of the date of death. Given the complexity of a Form 706 filing, working with a tax professional or estate attorney is worth the time, and reviewing taxes and final accounting obligations early can help you stay organized.
States with Estate Tax: 2026 Exemption Thresholds
Twelve states plus Washington D.C. (13 jurisdictions total) levy their own estate tax in 2026. That matters to you as executor because state thresholds are far lower than the federal $15 million exemption, meaning an estate that owes nothing federally can still owe state estate tax. As with the federal tax, the estate pays before any distributions go out.
Each state's revenue office publishes its own threshold, and the figures below come from those official pages for deaths in 2026. They range from $1 million in Oregon up to $15 million in Connecticut. Some states test the gross estate and others the taxable estate, so confirm the filing test with the state before you rely on a figure.
State
Exemption or Filing Threshold (2026 Deaths)
Official Source
Connecticut
$15,000,000
Hawaii
$5,490,000
Illinois
$4,000,000
Illinois Attorney General estate taxes
Maine
$7,160,000
Maine Revenue Services Form 706ME
Maryland
$5,000,000
Maryland Comptroller estate tax return
Massachusetts
$2,000,000
Minnesota
$3,000,000
Minnesota estate tax filing requirement
New York
$7,350,000
New York basic exclusion amount
Oregon
$1,000,000 (gross estate filing threshold)
Oregon DOR estate transfer tax
Rhode Island
$1,838,056
RI Division of Taxation advisory
Vermont
$5,000,000
Vermont Department of Taxes estate tax
Washington
$3,076,000 (deaths January 1 to June 30, 2026); $3,000,000 (deaths on or after July 1, 2026)
Washington D.C.
$4,988,400
Oregon's $1 million threshold is the lowest in the table and is measured against the gross estate, so a home plus a retirement account can cross it. New York has its own threshold rules, which our guide to the New York estate tax cliff walks through.
Data cited November 2026. Information subject to change.
Inheritance Tax by State: Which States Have Inheritance Tax
The states with inheritance tax in 2026 are Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Iowa's inheritance tax is fully repealed for deaths on or after January 1, 2025.
In every one of these states, surviving spouses pay nothing. Children are either fully exempt or taxed at low rates. Steeper rates apply to more distant relatives and unrelated heirs. Whether a state's inheritance tax applies generally depends on the decedent's domicile and where the property is located (situs) under that state's law, plus the beneficiary's relationship and any exemptions, not on where the beneficiary lives.
State
Spouse
Children/Lineal
Siblings
Others
Official Source
Kentucky
0%
0%
0% (Class A)
4% to 16% after a $1,000 exemption (Class B, such as nieces, nephews, aunts and uncles); 6% to 16% after a $500 exemption (Class C, all others)
Kentucky Department of Revenue
Maryland
0%
0%
0%
10% (nieces, nephews, aunts, uncles, cousins and unrelated heirs)
Nebraska
0%
1% above $100,000
1% above $100,000
11% above $40,000 (aunts, uncles, nieces, nephews and their descendants); 15% above $25,000 (all others)
Nebraska Revised Statute 77-2004
New Jersey
0%
0%
11% to 16% after the first $25,000 (Class C, siblings and a child's spouse)
15% up to $700,000, 16% above (Class D)
Pennsylvania
0%
4.5%
12%
15%
Pennsylvania Department of Revenue
Each state sets its own exemption amounts, filing deadlines, and relationship classes, so confirm the details with that state's revenue office. Pennsylvania has no estate-size threshold, so even small estates can owe tax, aside from narrow exemptions set by the Department of Revenue. Under Nebraska Revised Statutes 77-2004 through 77-2006, property passing to a beneficiary under age 22 is not subject to Nebraska inheritance tax. The sections below cover Pennsylvania in more detail, with notes on the other four states where relevant.
Data cited November 2026. Information subject to change.
Pennsylvania Inheritance Tax: What Executors Need to Know
Pennsylvania sits in a category of its own among inheritance tax states. It has no state estate tax, only an inheritance tax, and that tax applies regardless of estate size. There is no estate-size threshold to clear first, though specific transfers (such as to a spouse or charity) are exempt. A $40,000 estate can owe Pennsylvania inheritance tax just as surely as a $4 million one.
The Pennsylvania Department of Revenue sets rates by the beneficiary's relationship to the decedent:
0% on transfers to a surviving spouse, or to a parent from a child age 21 or younger
4.5% on transfers to direct descendants and lineal heirs
12% on transfers to siblings
15% on transfers to other heirs, except charities, exempt institutions and exempt government entities
Transfers to qualifying charities and government entities are exempt, as is jointly owned property between spouses. You'll typically need an EIN for the estate account to manage estate funds, so confirm the requirements with the IRS or a tax professional.
As executor, filing and payment typically fall on you. Pennsylvania inheritance tax is due at the date of death and becomes delinquent 9 months after that date, but pay within 3 months of death and the state allows a 5% discount on the tax owed. That discount is worth planning around, especially where the 12% and 15% rates apply.
States with Both an Estate Tax and an Inheritance Tax
Maryland is the only state that currently imposes both taxes. That means a Maryland estate can owe a state estate tax before any distributions go out, and a beneficiary may separately owe inheritance tax on what they receive. The two are coordinated rather than simply stacked: per the Maryland Comptroller, inheritance tax paid to the Register of Wills is subtracted from the gross Maryland estate tax before the estate tax bill is calculated.
Per the Maryland Register of Wills, a spouse, children and other lineal descendants, a child's spouse, stepchildren, parents, grandparents, and siblings are exempt from inheritance tax. Other beneficiaries, such as nieces, nephews, aunts, uncles, cousins, and unrelated heirs, generally pay 10%. For those beneficiaries, the estate may first owe Maryland estate tax, and their share may then owe inheritance tax, with the inheritance tax credited against the estate tax as described above.
Every other state covered here lands in one column or the other. Massachusetts, Oregon, and Washington levy an estate tax with no inheritance tax. Pennsylvania, New Jersey, Kentucky, and Nebraska levy an inheritance tax with no estate tax. Your filing obligations differ considerably depending on which regime applies, so verify current rules with the relevant state revenue authority before filing anything.
States with No Inheritance Tax or Estate Tax
Most states impose no state-level estate or inheritance tax at all. The majority of the 50 states fall into this category, so a decedent domiciled there typically leaves beneficiaries without a state death tax reducing the estate beforehand or arriving as a separate bill afterward. That said, owning real estate or other property located in a state that does levy one of these taxes can still trigger a filing obligation there under that state's own rules, regardless of where the decedent lived.
Federal estate tax still applies wherever your loved one lived. If the gross estate exceeds the $15,000,000 federal exemption for 2026 deaths, Form 706 is due 9 months after the date of death.
For executors in states like Florida, Texas, California, or Colorado, the decedent's home state typically adds no estate or inheritance tax, though you'll still need to manage an estate account for federal filings and distributions. The death-tax work is usually federal only, unless property sits in another state that taxes it, and for most estates, even the federal threshold won't be crossed.
Who Pays Estate Tax and Who Pays Inheritance Tax
For estate taxes, federal or state, the executor or personal representative typically files the return and pays the bill from estate funds, and distributions wait until the tax is settled. Distributing before the tax is settled can expose a fiduciary to liability for unpaid tax in some situations, and the rules differ by jurisdiction, so check with your tax professional or attorney before distributing.
Inheritance tax is generally owed on each beneficiary's share. In some states, such as Pennsylvania, the personal representative files the inheritance tax return, and the tax is often paid from the estate or withheld from a share before distribution. Who files and pays differs by state and by the will's terms, so confirm the process with that state's revenue office.
One practical wrinkle worth knowing: some inheritance tax states may require a tax waiver or release before certain banks, brokerages, or transfer agents will release assets held in your loved one's name. Whether one is needed depends on the state, the type of asset, and the beneficiary's relationship to the decedent. Ask that state's revenue office early, since you may need to start that process before you can move money at all, so it's worth adding this step to your executor checklist.
What Assets Are Subject to Each Tax
What counts as a taxable asset depends on which tax you're dealing with and which state you're in.
For federal estate tax, the IRS casts a wide net. The gross estate generally includes everything the decedent owned or controlled at death: real property, bank and brokerage accounts, retirement accounts, business interests, personal property, and life insurance proceeds where the decedent held incidents of ownership over the policy. The key word is "controlled." Assets held in certain trusts, or where the decedent retained rights over the proceeds, can still land in the gross estate even if they never touched probate.
Inheritance tax states focus on a simpler question: what did each beneficiary actually receive? The tax attaches to the transferred amount, not the estate's total value. A beneficiary who inherits $80,000 from a $1.2 million estate is generally taxed on that $80,000, subject to that state's exemptions and rate class.
A common point of confusion involves assets that pass outside of probate. Jointly held property with right of survivorship, payable-on-death accounts, and beneficiary-designated retirement accounts all transfer directly to the named recipient without going through the will. That does not make them tax-free. Many of these assets are still counted in the federal gross estate. Whether they are subject to state inheritance tax depends on the state, since some states exempt certain assets such as life insurance or specific retirement benefits.
How the Two Taxes Affect Your Timeline as Executor
Deadlines for these taxes vary by state, so check the rules where the estate is being settled before you set your own timeline. The federal estate tax return, Form 706, is due 9 months from the date of death. Pennsylvania's inheritance tax becomes delinquent on that same 9-month mark, though filing and paying within 3 months earns a 5% discount. Other states run on different clocks: Kentucky gives you 18 months to file and pay its inheritance tax, with a 5% discount if paid within 9 months, while the D.C. estate tax return is generally due 10 months after death. These deadlines run from the date of death, not from your appointment, so confirm the applicable deadline for each state where the decedent was domiciled or owned property as early as you can.
That window sounds generous until you map out what comes first. Before filing, you will usually need date-of-death values for estate assets, which can mean gathering account statements from every institution and, for assets like real estate or a business, getting a valuation. These steps often overlap with creditor claims and the rest of the work covered in our probate timeline guide, so tax filings tend to land in the middle of an active settlement.
As part of distributing assets and closing the estate, holding distributions until applicable taxes are calculated and paid is generally the cautious approach. That hold protects beneficiaries as well as you.
How Alix Helps Executors Handle Estate and Inheritance Tax Obligations
Alix's estate settlement service works alongside your tax professional or attorney to coordinate estate tax filings as part of settlement. That coordination keeps federal and state filing dates in view; for the full sequence, see our guide to settling an estate.
Final Thoughts on Estate and Inheritance Tax Obligations
The core takeaway is straightforward: know which tax applies, who pays it, and when the deadline lands before you move a single dollar. State rules vary enough that Oregon's $1 million threshold and Pennsylvania's no-floor inheritance tax can surprise even careful executors. The federal Form 706 deadline and Pennsylvania's delinquency date both fall 9 months after death, but other states, such as Kentucky, run on different clocks, and every one of those clocks starts at the date of death. Connect with an Alix specialist to work through the tax obligations specific to your estate.
FAQ
What is the difference between inheritance tax and estate tax?
Estate tax is charged against the estate itself before any distributions go out, and you typically file and pay it from estate funds during settlement. Inheritance tax is charged to each beneficiary based on what they receive, with rates that depend on their relationship to the decedent and the state involved. Who actually files and pays inheritance tax varies by state, so confirm the process where the estate is being settled.
Is there a federal inheritance tax?
No, there is no federal inheritance tax. The federal government taxes large estates once, at the estate level, through the federal estate tax, so what you receive as a beneficiary is not separately taxed by the IRS. Whether you owe anything still depends on where the decedent lived, since a state inheritance tax may apply even though no federal version exists.
Which states have inheritance tax?
Five states levy an inheritance tax in 2026: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Iowa repealed its inheritance tax for deaths on or after January 1, 2025, so it no longer applies there. In all five remaining states, surviving spouses are exempt, and rates typically rise the more distantly a beneficiary is related to the person who died. If the decedent was domiciled elsewhere, a state inheritance tax generally won't apply, unless the decedent owned property located in one of these five states, in which case that state may tax the transfer under its own rules.
Which states have both an estate tax and an inheritance tax?
Maryland is the only state that currently imposes both. Spouse, children and other lineal descendants, a child's spouse, stepchildren, parents, grandparents, and siblings are exempt from Maryland's inheritance tax. Nieces, nephews, aunts, uncles, cousins, and unrelated heirs generally pay 10%. Inheritance tax paid is credited against the Maryland estate tax, so the combined bill ends up lower than simply adding the two taxes together.
What is the federal estate tax exemption in 2026, and when is Form 706 due?
For deaths in 2026, the federal estate tax exemption is $15,000,000 per person, per the IRS. If the gross estate exceeds that threshold, you file Form 706, due 9 months after the date of death, and the top federal rate is 40% on amounts above the exemption. If the estate falls below the threshold, no federal estate tax return is required.
Who pays estate tax and who pays inheritance tax?
As executor, you typically file and pay estate tax from estate funds before any distributions go out. Inheritance tax is generally owed on each beneficiary's share; in some states the personal representative files the return, and the tax may be paid from the estate or withheld from a beneficiary's share, depending on the state and the terms of the will. Practices vary by state, so confirm the requirements with that state's revenue office before distributing.
What's the fastest way to reduce what a Pennsylvania estate owes in inheritance tax?
Pay within 3 months of the date of death, and Pennsylvania gives you a 5% discount on the tax owed. The tax becomes delinquent 9 months after death, so missing the 3-month window costs you the discount, and paying after 9 months adds interest.

Related resources