When the last borrower on a reverse mortgage passes, the loan comes due, and whoever is handling the estate has to figure out what happens next. That's typically the executor, and the job isn't to pay off a debt out of pocket. It's to decide what to do with the home before the servicer's deadline runs out. Here's a clear look at how that responsibility works and what your options actually are.
Key Takeaways:
- Heirs are not personally liable for a reverse mortgage; the debt is limited to the home itself under HECM non-recourse rules.
- As executor, you carry the decision-making obligation: respond to the servicer promptly or your timeline compresses fast.
- You generally have around 30 days to signal intent, with extensions possible up to roughly 12 months in many cases, subject to servicer approval and HUD guidelines.
- Four resolution paths exist: sell, refinance, pay the balance directly, or deed-in-lieu, depending on equity and your goals.
- Alix coordinates the full settlement: an attorney from Alix's network handles probate filings, while Alix's specialists handle property coordination, creditor correspondence, and more than 150 administrative tasks, under one transparent fee paid from the estate.
What a Reverse Mortgage Is and How It Becomes Due
A reverse mortgage lets homeowners aged 62 or older borrow against their home's equity without making monthly payments. The loan balance grows over time as interest accrues and fees accumulate, while the home stays in the borrower's name with the lender holding a claim against it.
The most common type is the Home Equity Conversion Mortgage (HECM), federally insured through FHA. As the CFPB explains, reverse mortgage loans typically must be repaid when the last borrower dies, usually by selling the home. The loan does not transfer to heirs as an ongoing obligation; it comes due in full at death.
Proprietary reverse mortgages also exist, and their terms can differ meaningfully from HECM rules. If the loan documents do not reference FHA or HUD, the timeline and options may look different, so checking the actual loan agreement first is worth doing.
Who Is Actually Responsible for the Debt
Heirs are responsible for deciding what happens to the home. They are not personally responsible for the debt itself.
That distinction matters. Under a HECM, the loan is non-recourse, meaning the lender's recovery is limited to the home. If the loan balance exceeds what the property is worth, heirs are not required to cover the gap out of pocket. As the CFPB explains, heirs must repay the full loan balance or at least 95% of its appraised value if the balance exceeds what the home is worth. The shortfall stops there.
What heirs do carry is a decision-making obligation. The home cannot simply sit. Someone needs to respond to the servicer, assess the options, and act within the required window. If you're the executor, that responsibility lands with you, even if the debt itself never does.
How Responsibility Varies Depending on Who Is Left Behind
Not everyone left behind faces the same situation. Which category you fall into determines what you can do next.
Co-Borrower on the Loan
If a co-borrower was named on the loan, they can remain in the home and continue receiving payments, as long as they keep up with property taxes, insurance, and maintenance, per the CFPB. The loan does not become due simply because one borrower passed.
Eligible Non-Borrowing Spouse
A surviving spouse who was not on the loan may still qualify to stay in the home without triggering repayment, but only if the HECM has an FHA case number assigned on or after August 4, 2014, and they meet HUD's eligibility criteria. This protection does not extend to all spouses automatically.
Heirs With No Loan Protections
Everyone else, including adult children, siblings, or other heirs, has no right to remain. The loan is due, and the executor is responsible for managing the response and the property decision.
What the Due-and-Payable Notice Means and What Happens Next
The due-and-payable notice is not a foreclosure filing. It is a formal notification that the loan has come due and that the estate has a window to respond.
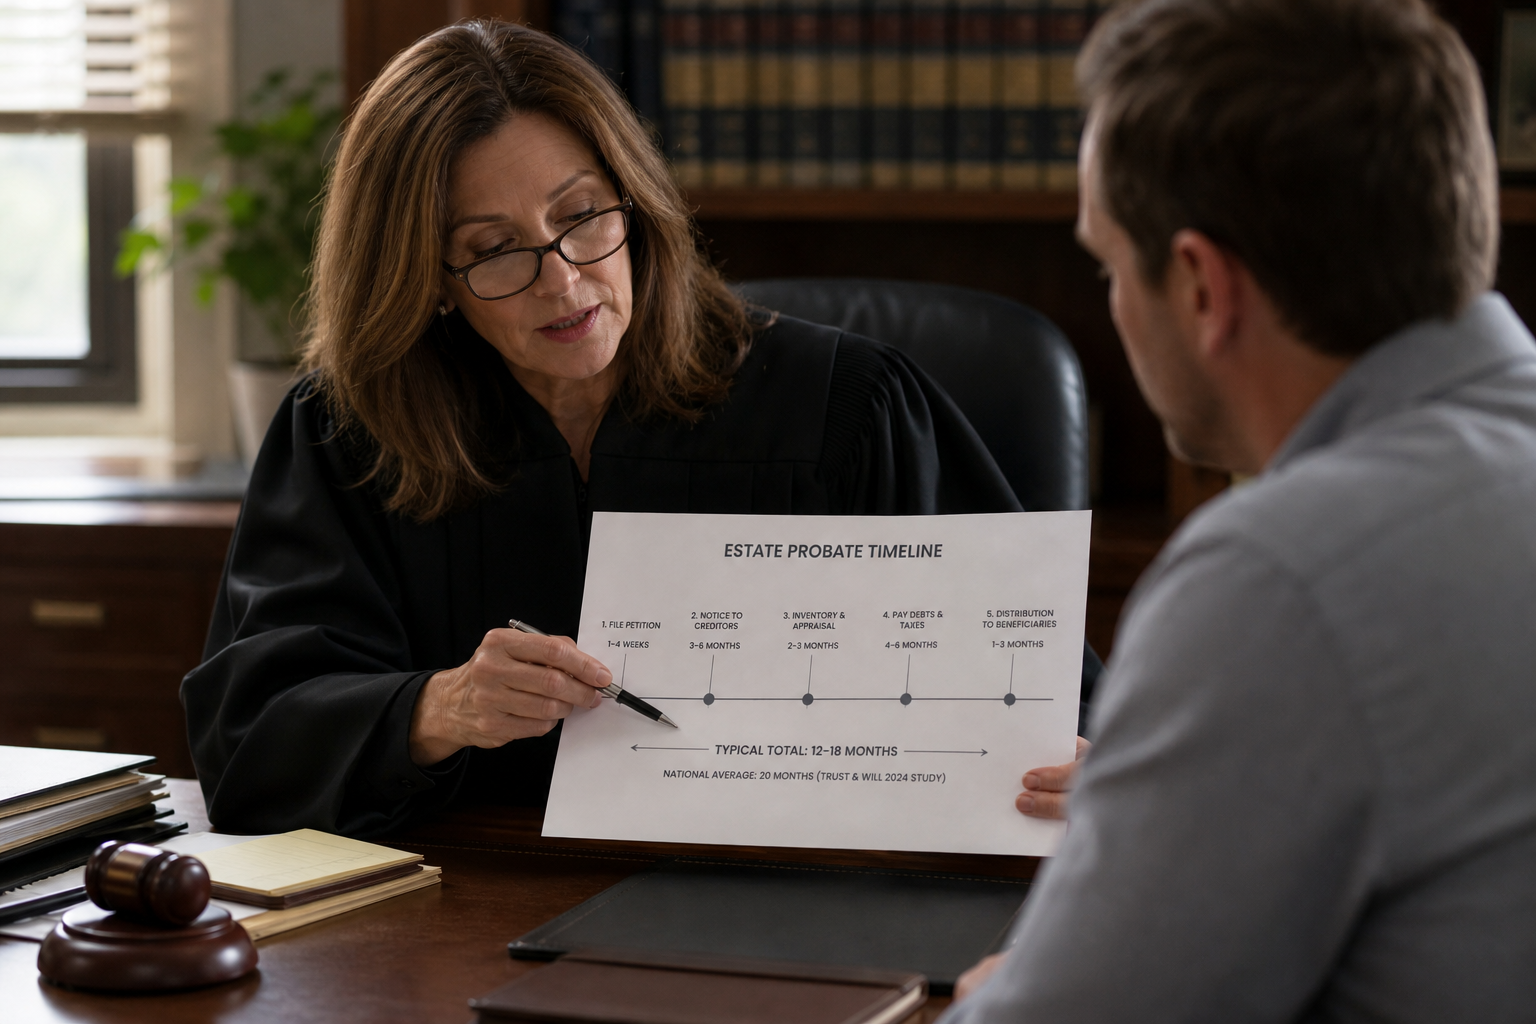
According to the CFPB, the lender issues the due-and-payable notice to the estate within 30 days of learning of the borrower's death. Once heirs receive that notice, they generally have around 30 days to indicate their intent to buy, sell, or turn the home over to the lender. That window is a response deadline, not a closing deadline. The timeline can typically be extended up to six months to allow heirs to sell or secure financing, and HUD may approve two additional three-month extensions, bringing the ceiling to around 12 months in many cases, subject to servicer approval and HUD guidelines.
What makes the difference is staying in active contact with the servicer. Ignoring the notice, or going quiet after the first response, is where timelines compress quickly. Prompt engagement keeps options open.
Data cited November 2026. Information subject to change.
The Four Options for Settling a Reverse Mortgage After Death
Once the due-and-payable notice arrives, there are four ways to resolve the loan. None is universally better than another. The right path depends on the home's equity, the heir's finances, and what the family wants to do with the property.
| Option | Who It Fits | Key Requirement | What Happens to the Home |
|---|---|---|---|
| Sell the home | Heirs who don't want to keep the property and there is meaningful equity | Executor authority (Letters Testamentary) to sign transfer documents | Sold; loan paid from proceeds; remaining equity goes to estate |
| Refinance / new mortgage | An heir who wants to keep the home and can qualify for a loan | Heir must independently qualify for a conventional mortgage | Kept by heir; reverse mortgage paid off with new loan |
| Pay balance directly | Estate or heir with sufficient liquid assets | Funds available to cover the payoff amount (up to 95% of appraised value for HECM) | Kept or transferred; no new debt taken on |
| Deed-in-lieu of foreclosure | Loan balance equals or exceeds home value; no one wants the property | Executor signs property over to lender | Transferred to lender; no sale process or ongoing carrying costs |
- Sell the home. The most common path. Proceeds pay off the loan balance, and any remaining equity goes to the estate. This route works best when there is meaningful equity and no one wants to keep the property. A probate sale follows specific court-supervised steps that differ from a standard real estate transaction.
- Refinance or take out a new mortgage. If an heir wants to keep the home, they can pay off the reverse mortgage by taking out a conventional mortgage in their own name. This requires qualifying for a loan independently, and makes sense when the heir has the credit and income to carry it.
- Pay the balance directly. If the estate or an heir has liquid assets, the loan can be paid off outright without taking on new debt. Less common, but a real option worth knowing.
- Deed-in-lieu of foreclosure. The executor signs the property over to the lender. No sale process, no ongoing carrying costs. This typically makes sense when the loan balance approaches or exceeds the home's value.
For HECM loans, the payoff amount is generally capped at 95% of the appraised value even if the loan balance is higher, which affects the math on the last two options in particular.
What Happens When the Loan Balance Exceeds the Home's Value
Under HECM non-recourse rules, the lender's recovery is limited to the property itself. According to the the CFPB, heirs can satisfy the debt by paying 95% of the appraised value, even if the outstanding balance exceeds that figure. The shortfall is absorbed by FHA's insurance fund, not passed to the family.
Proprietary reverse mortgages may not carry the same protection. Non-recourse language varies by lender and loan agreement, so reading the actual promissory note matters before assuming HECM rules apply.
The Executor's Role When Probate Is Required
When probate is required, the executor's role begins with obtaining legal authority to act. If the property was titled solely in your loved one's name with no transfer-on-death designation, probate is typically required before you can sell or otherwise resolve the home. The servicer clock starts at death, but your authority to act does not exist until a probate court appoints you. Getting Letters Testamentary or Letters of Administration in hand quickly is one of the first practical priorities, since you cannot negotiate a sale or sign transfer documents without them.
Once appointed, you carry several concrete obligations:
- Respond to the servicer and keep them updated on probate status so they know the estate is actively moving forward.
- Maintain property insurance on a vacant home, since many standard policies restrict or cancel coverage after 30 to 60 days of vacancy.
- Pay property taxes and any HOA fees to avoid triggering separate default conditions on top of the loan.
- Secure and maintain the property to protect its appraised value against deterioration.
Staying in contact with the servicer, even before probate closes, signals active intent and generally keeps them from accelerating toward foreclosure.
How Fraud, Solicitation, and Estate Scams Target Reverse Mortgage Homes
Reverse mortgage estates are more visible than most executors expect. When the last borrower passes, property records update, death notices circulate publicly, and solicitation mail starts arriving fast, often before you've had time to locate the will.
That visibility creates real exposure. Fraudulent creditors, unsolicited deed service companies, and identity thieves all show up once a home with equity is identifiable through public records. Acting in the first few weeks closes most of those windows early.
A few steps worth handling right away:
- Notify all three credit bureaus (Equifax, Experian, TransUnion) of the death to place a deceased alert on the borrower's file, which blocks new credit from being opened in their name.
- Register with the DMAChoice deceased mail suppression service to reduce solicitation mail addressed to your loved one.
- Alert the Social Security Administration, which shares death data with financial institutions and cuts down on fraudulent benefit claims.
- Keep monitoring mail at the property address, since fraudulent lien notices and deed service scams commonly target vacant homes during the probate window.
None of these steps require probate authority to initiate, so you can start them immediately.
How Alix Helps Executors Manage a Reverse Mortgage Estate
Reverse mortgage estates come up often in Alix's work with executors, and the pattern is consistent: a servicer deadline on the family home, often arriving while probate is still opening. Across our client files, 222 notes reference a reverse mortgage, a figure that has grown steadily month over month through mid-2026. These are real executors facing a real deadline on the family home, often while probate is still opening.
The servicer notice is just the starting point. Behind it sits a full estate: probate filings to confirm your legal authority, property coordination including locksmith access, utility transfers, insurance continuation, and routine maintenance on a vacant home, creditor correspondence, tax filing, and beneficiary communication, all running while the servicer clock ticks. The deadline compresses everything else.
Alix's estate settlement specialists handle more than 150 administrative tasks that do not require a law license, coordinating them as one process alongside an attorney from Alix's network who handles the licensed legal work for standard probate and settlement. That attorney is included in Alix's one transparent fee, which is paid from the estate, not out of your pocket, regardless of whether the jurisdiction requires formal probate. Court filing fees, legal notice publication costs, and vendor costs like appraisals and real estate services are typically paid by the estate separately. If you already have your own attorney, that works too; those fees are handled separately, outside of Alix's fee.
Alix is built for reverse mortgage estates with real complexity: a home with equity, probate to open, and accounts, creditors, and beneficiaries to coordinate. If the loan balance exceeds the home's value and little else is in the estate, a deed-in-lieu handled directly with the servicer may be the simpler path. Alix also steps in only once any will contest, executor challenge, or beneficiary dispute is fully resolved.
Final Thoughts on Who Is Responsible for a Reverse Mortgage After Death
The window is real, the options are workable, and staying in front of the servicer makes a bigger difference than most executors expect. If the estate includes a reverse mortgage and a home with equity, start your Alix onboarding to get a settlement specialist in your corner.
FAQ
Are heirs personally responsible for a reverse mortgage balance that exceeds the home's value?
No. Under a HECM's non-recourse rules, heirs are never required to cover a shortfall out of pocket. The lender's recovery is limited to the home itself. If the loan balance exceeds the appraised value, heirs can satisfy the debt by paying 95% of that appraised value, and FHA's insurance fund absorbs the rest. Proprietary reverse mortgages may not carry the same protection, so checking the actual loan documents matters before assuming HECM rules apply.
Who is responsible for a reverse mortgage after death if the surviving spouse was not on the loan?
It depends on whether the spouse qualifies as an eligible non-borrowing spouse. If the HECM carries an FHA case number assigned on or after August 4, 2014, and the spouse meets HUD's eligibility criteria, they can generally stay in the home without triggering repayment. Otherwise, the loan comes due and the executor is responsible for responding to the servicer and managing the property decision. Adult children and other heirs have no right to remain in the home.
How do I protect my loved one's estate from fraud and solicitation after a reverse mortgage comes due?
You can start these steps right away, without probate authority. Notify all three credit bureaus (Equifax, Experian, and TransUnion) to place a deceased alert on the borrower's file, which blocks new credit from being opened in their name. Register with DMAChoice's deceased mail suppression service to cut solicitation mail, and alert the Social Security Administration so death data reaches financial institutions. Keep monitoring mail at the property address, since fraudulent lien notices and deed service scams frequently target vacant homes during the probate window.
What are my options for settling a reverse mortgage after the borrower's death?
There are four paths: sell the home and use proceeds to pay off the loan; refinance with a conventional mortgage in your own name if you want to keep the property; pay the balance directly if the estate has liquid assets; or sign a deed-in-lieu of foreclosure, which transfers the property to the lender with no sale process. For HECM loans, the payoff is generally capped at 95% of appraised value even when the loan balance is higher, which affects the math on the last two options.
Can I negotiate with the reverse mortgage servicer before probate closes?
Yes, and you should. The lender issues the due-and-payable notice within 30 days of learning of the death; once you receive it, you generally have around 30 days to signal intent. Your legal authority to sign documents or execute a sale does not exist until a probate court appoints you and you have Letters Testamentary in hand, but staying in active contact with the servicer in the meantime, updating them on probate status and signaling that the estate is moving forward, generally keeps them from accelerating toward foreclosure. Ignoring the due-and-payable notice, even temporarily, is where timelines compress fastest.

Related resources